Showing posts with label mortgage interest rates. Show all posts

Wednesday, April 19, 2017

Home Mortgages: Rates Up, Requirements Easing

Home Mortgages: Rates Up, Requirements Easing


Home Mortgages: Rates Up, Requirements Easing - The media has extensively covered the rise in mortgage interest rates since last fall (from 3.42% last September to the current 4.1% according to Freddie Mac). However, a less covered aspect of the mortgage market is that requirements to get a mortgage have eased while rates have risen.
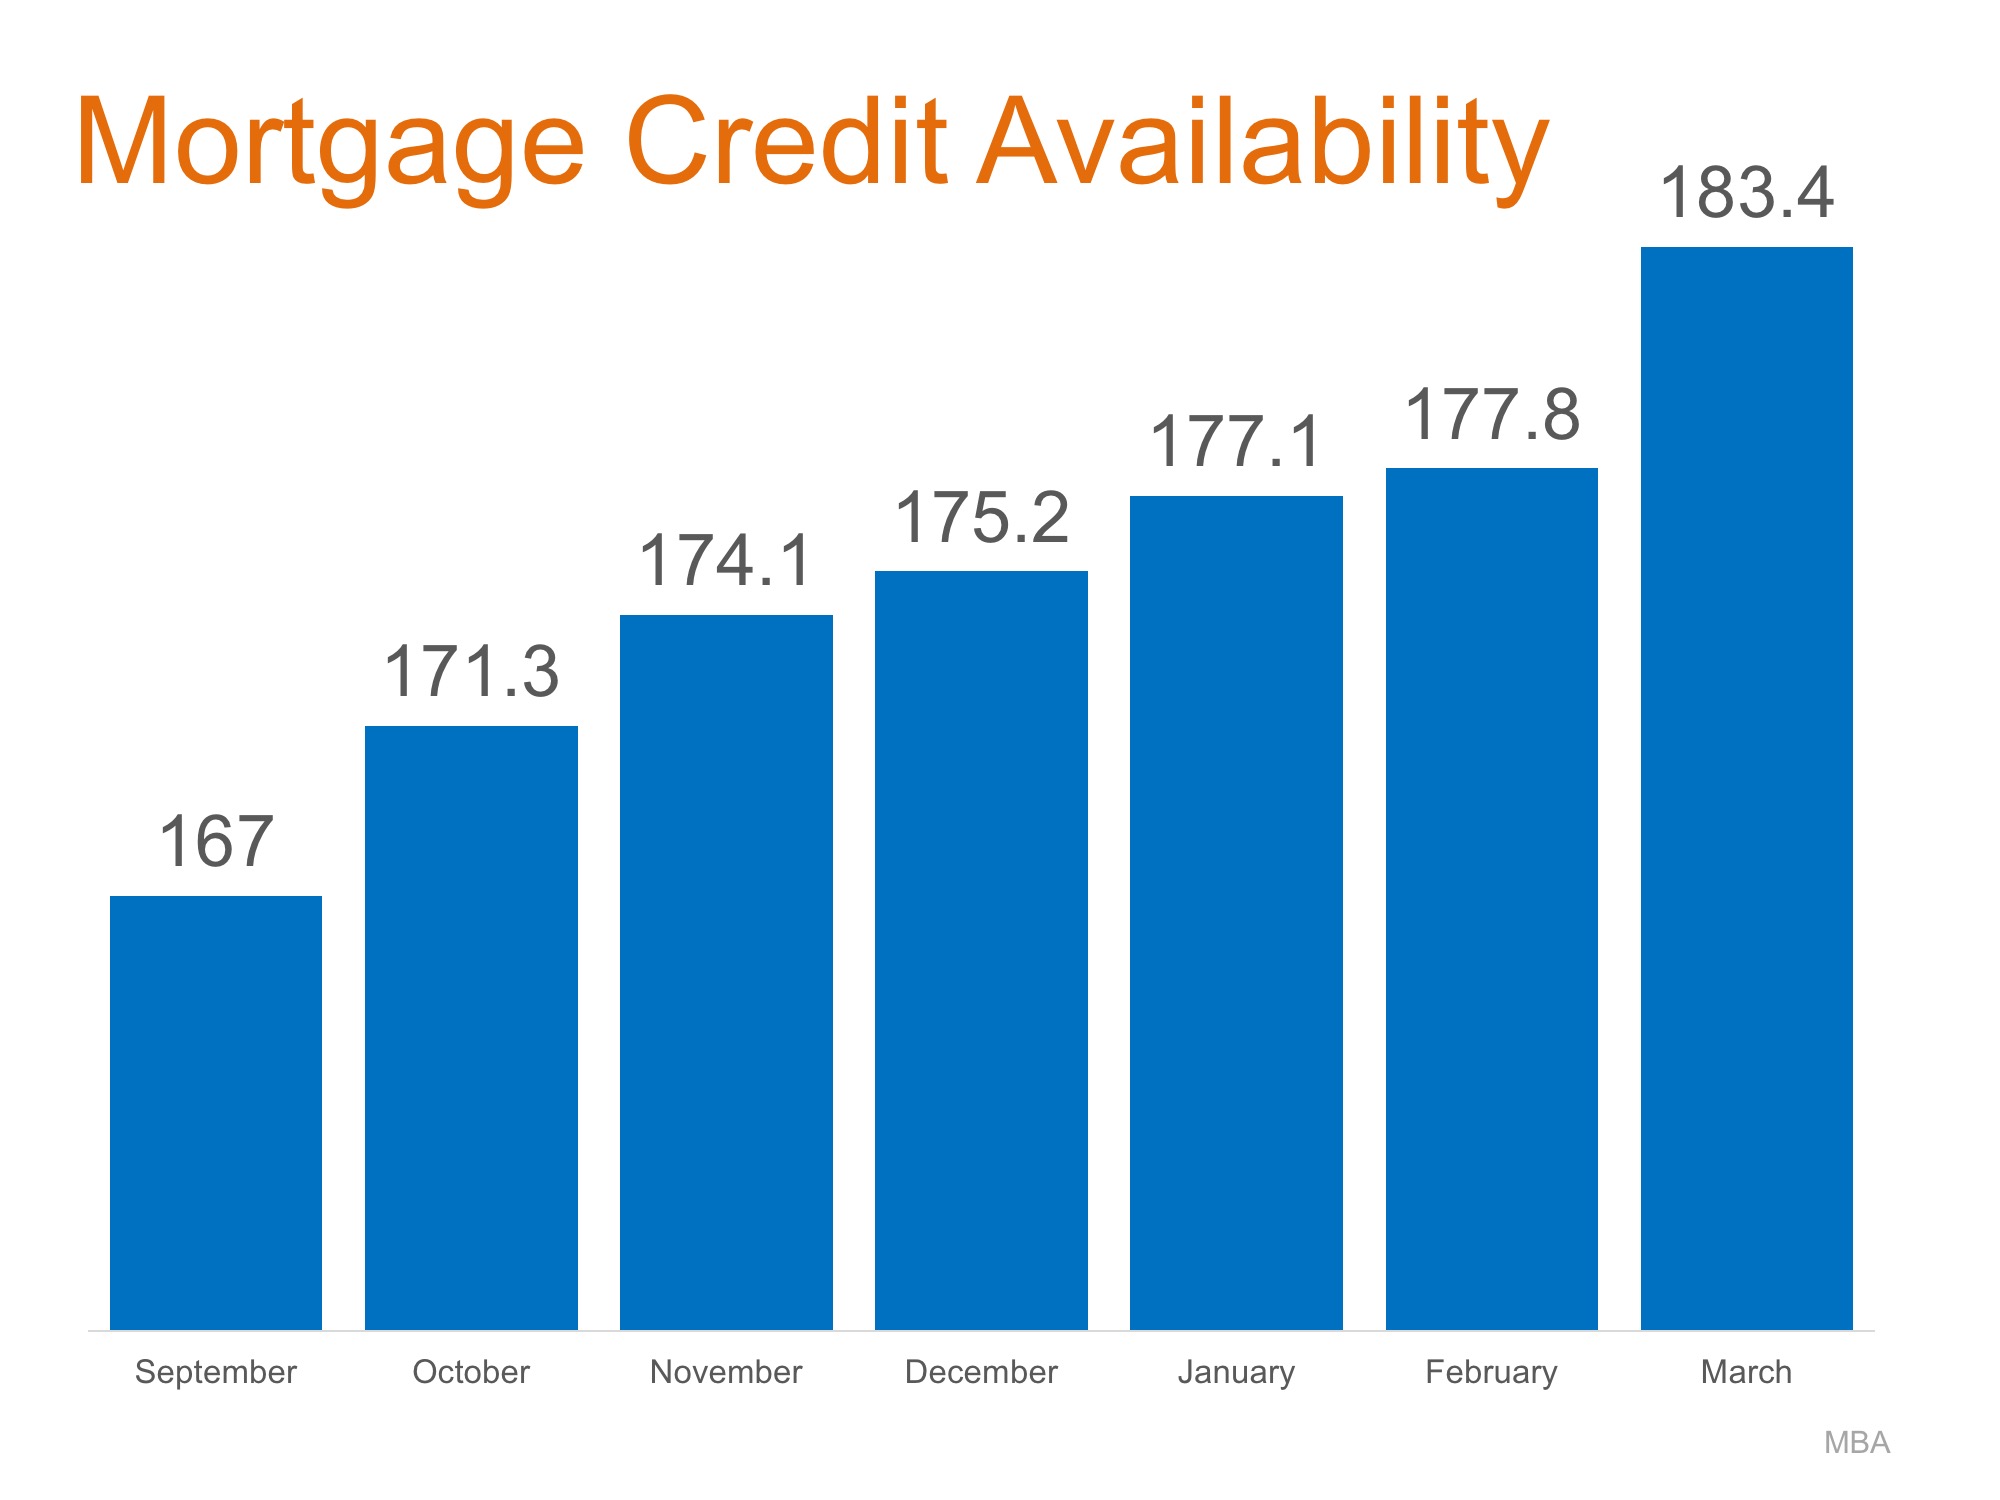
The Mortgage Bankers Association (MBA) quantifies the availability of mortgage credit each month with their Mortgage Credit Availability Index (MCAI). According to the MBA, the MCAI is:
“A summary measure which indicates the availability of mortgage credit at a point in time.”
The higher the index, the easier it is to get a mortgage. Here is a chart showing the MCAI over the last several months as rates have increased.
Home Mortgages: Rates Up, Requirements Easing | MyKCM

Have requirements for attaining a mortgage actually eased?

Yes. Here are two examples:
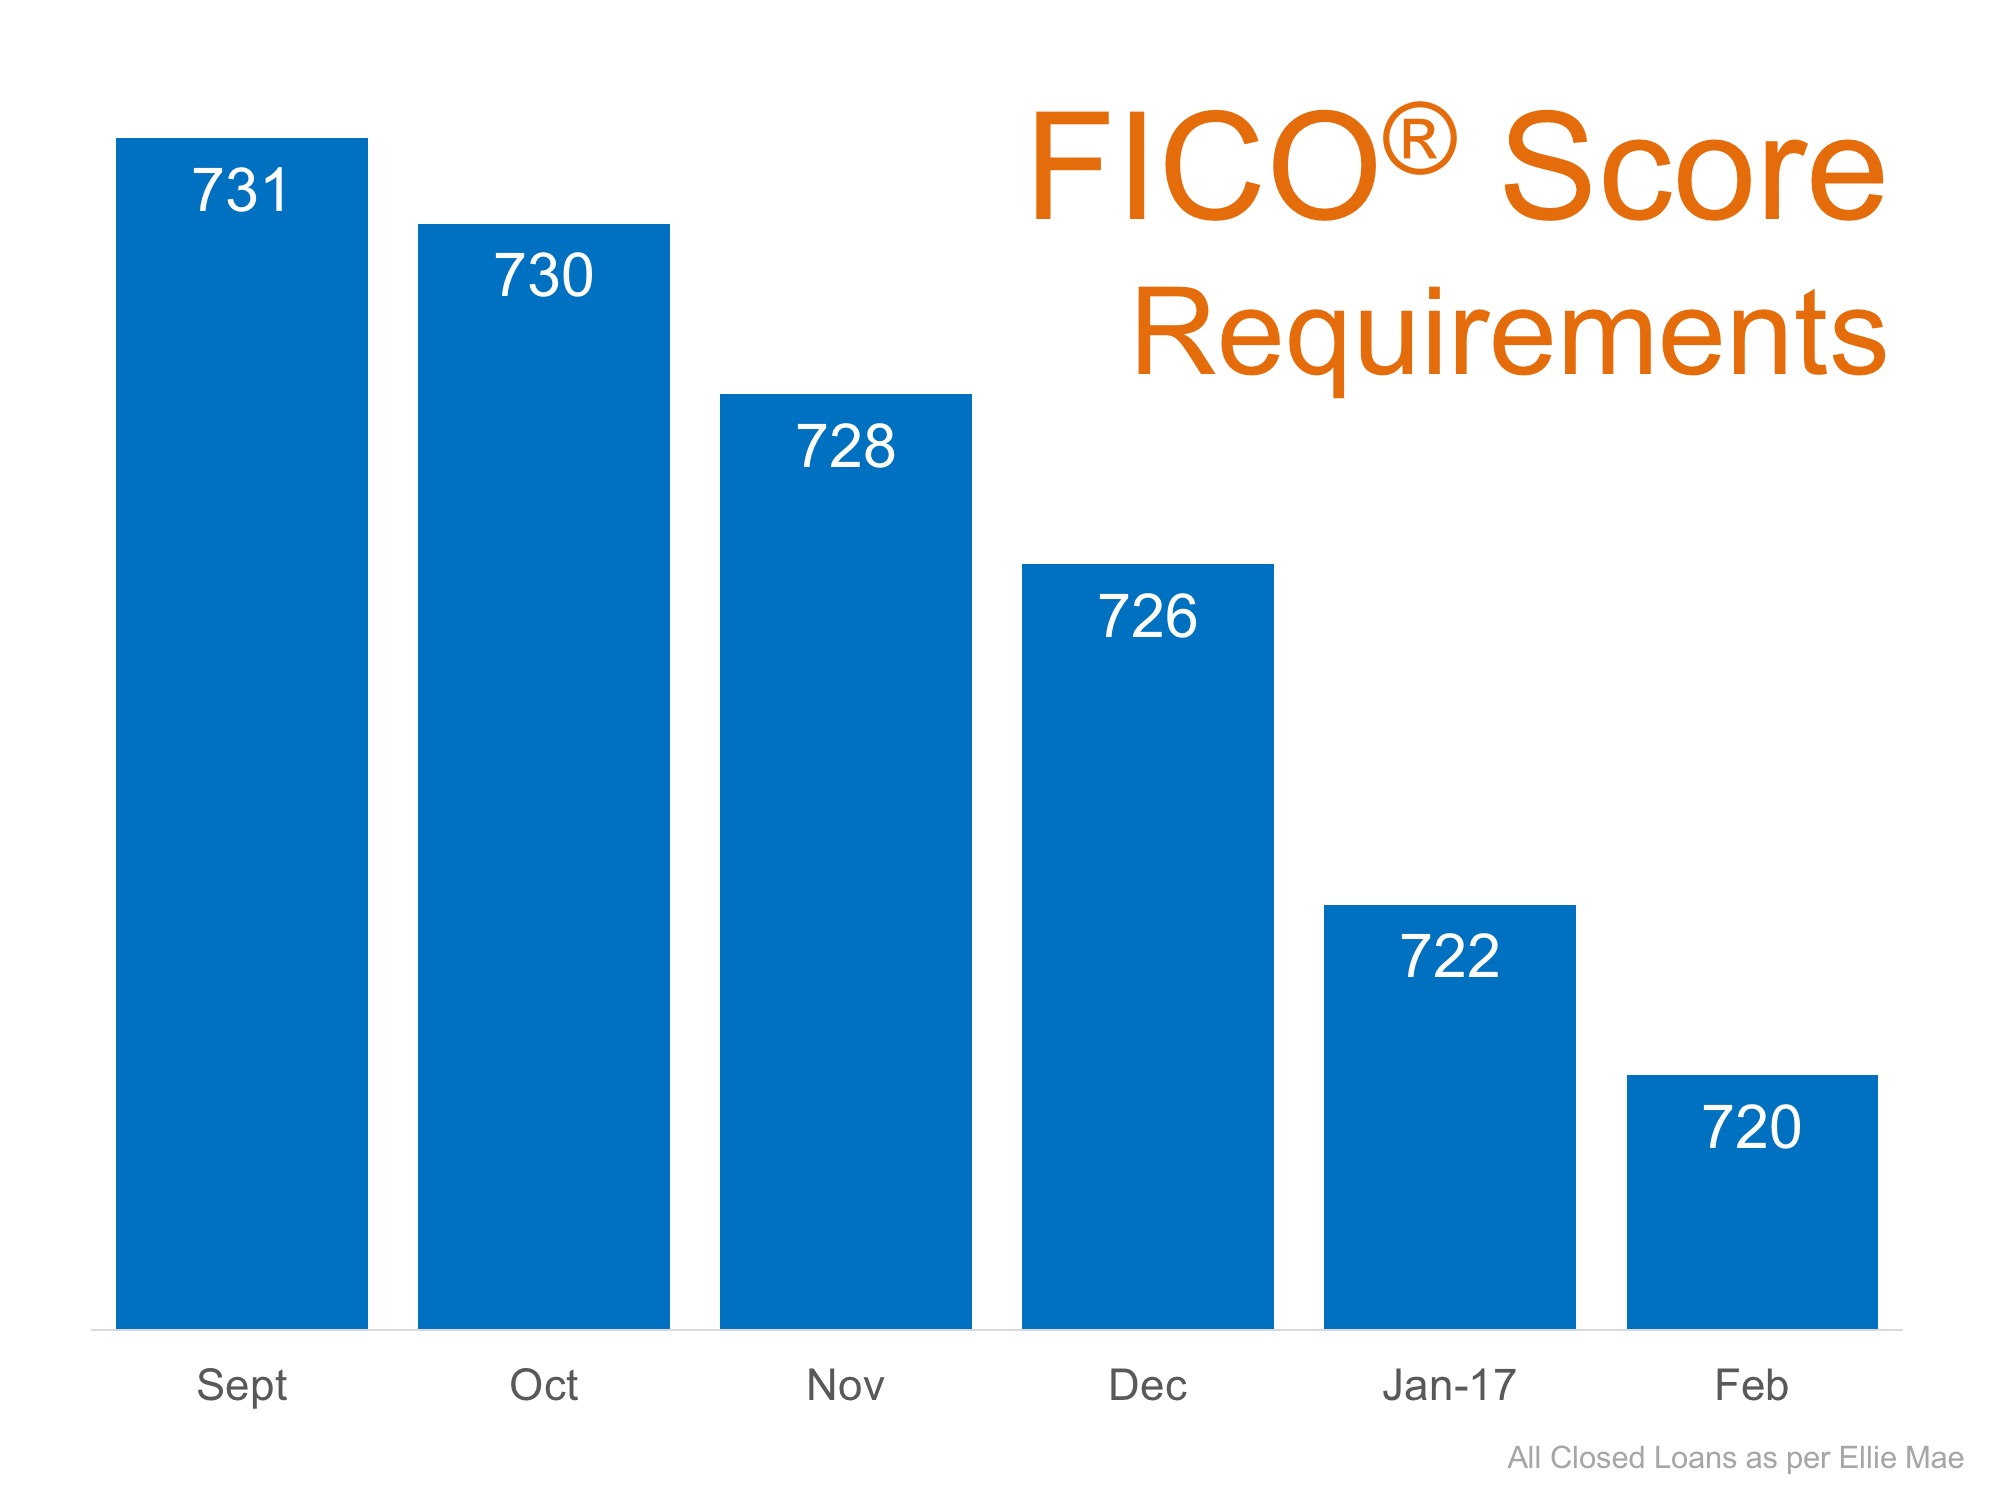
  1. FICO® Score – the credit score which helps determine a buyer’s eligibility. The score required to attain a mortgage has been falling over the last five months:
Home Mortgages: Rates Up, Requirements Easing | MyKCM
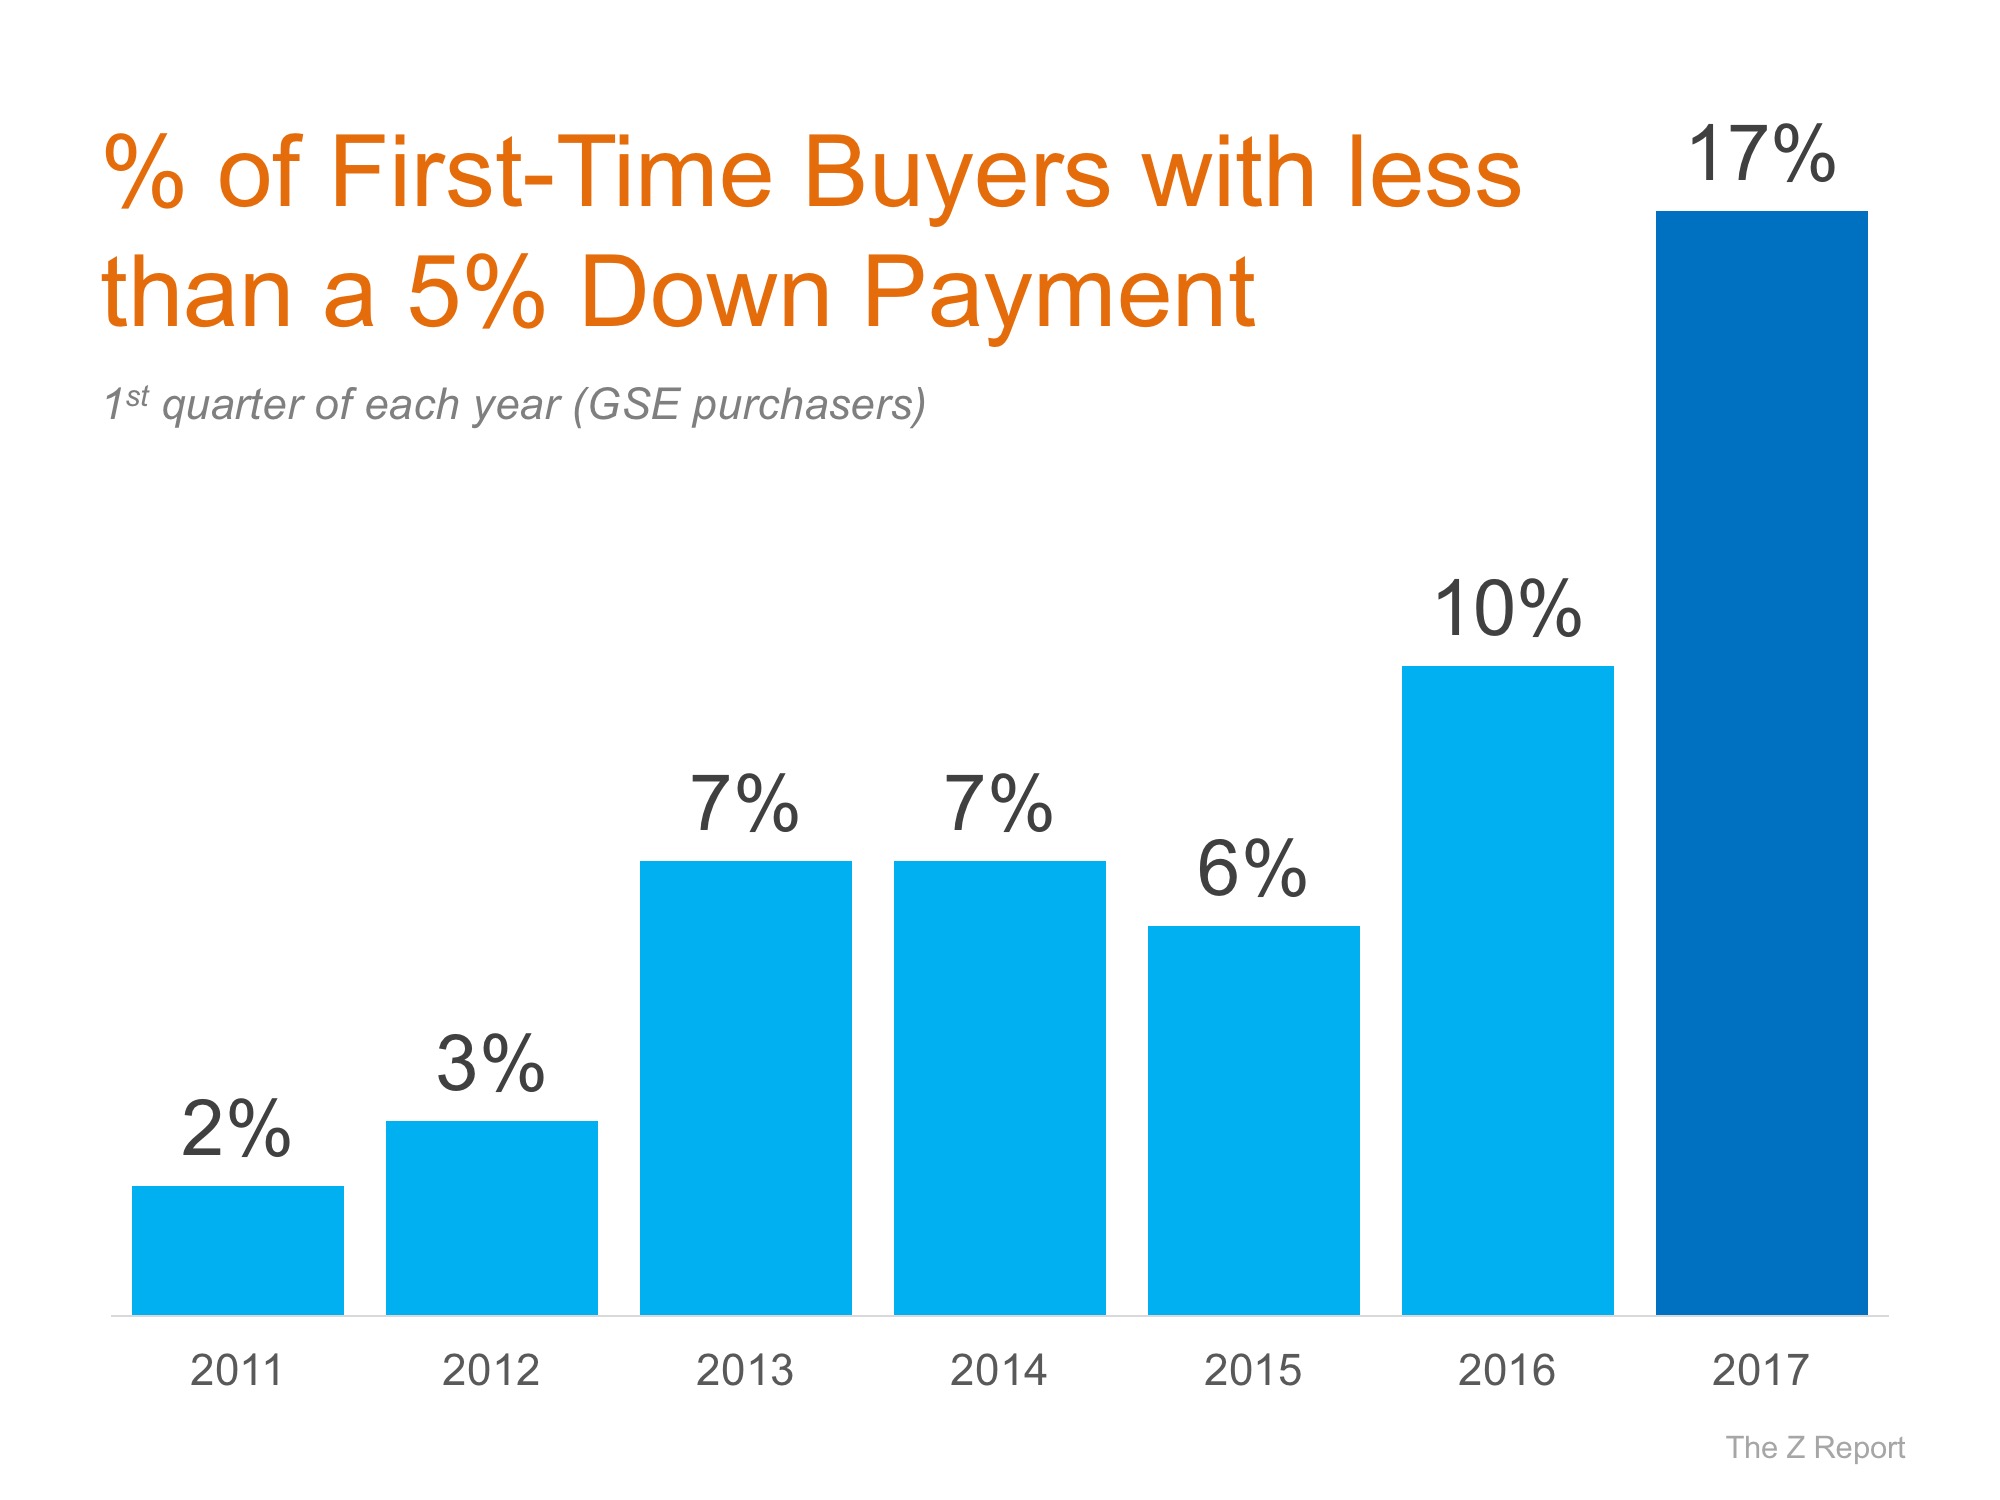
  1. Down Payment Requirement – the percentage of the purchase price necessary to place as a down payment on a home. To make this point, let’s look at the percentage of first-time buyers who have put less than 5% down over the last several years as compared to the 1st quarter of 2017:
Home Mortgages: Rates Up, Requirements Easing | MyKCM

Bottom Line

Whether you are a current homeowner looking to move to a home that will better serve your family’s current needs, or a first-time buyer looking for a starter home, it is easier to get a mortgage today than it has been at any other time in the last ten years.


To See More Blogs Like This One Please Visit My Website 
For More Info Please Call 909-697-0823
or Visit

Thursday, April 6, 2017

What Are the Experts Saying about Mortgage Rates?

What Are the Experts Saying about Mortgage Rates?


What Are the Experts Saying about Mortgage Rates? - Mortgage interest rates have risen over the last few months and projections are that they will continue their upswing throughout 2017. What impact will this have on the housing market? Here is what the experts are saying:
“In 1984, 1994, 2000, and 2013, every time we have rate increases, we have increases in nominal home prices. We expect this to be more pronounced, as there is a big demand-and-supply gap at the present time.”
“The tightening labor market, rising wage growth, high levels of consumer confidence and a millennial generation with a pent-up demand for housing should allow the housing market to weather the storm of gradually rising interest rates.”
“Although we strongly believe that the housing supply-demand imbalance for single-family homes will continue to drive above-average home price appreciation, just as falling mortgage rates aided pricing power on the margin in recent months, we expect the opposite effect to become evident in the coming months. As such, we project year-end home price inflation of 4.8% for 2017 and 4.1% for 2018.”
“A modest increase in mortgage rates won’t have much of an effect on home purchases. A buyer may need to slightly re-evaluate which homes they can afford, but it’s not likely to make an impact on qualifying, in most cases.”
"Our survey data shows that mortgage rates would have to be significantly higher to have any meaningful impact. The house buying power that borrowers have, even with rates below five percent, still remains historically strong."
To See More Blogs Like This One Please Visit My Website 
For More Info Please Call 909-697-0823
or Visit

Tuesday, April 4, 2017

It's a Seller's Market! Should I Downsize Now?


It's a Seller's Market! Should I Downsize Now?


It's a Seller's Market! Should I Downsize Now? - A study by Edelman Berland reveals that 33% of homeowners who are contemplating selling their houses in the near future are planning to scale down. Let’s look at a few reasons why this might make sense for many homeowners, as the majority of the country is currently experiencing a seller’s market.
In a blog, Dave Ramsey, the financial guru, highlighted the advantages of selling your current house and downsizing into a smaller home that better serves your current needs. Ramsey explains three potential financial advantages to downsizing:
  1. A smaller home means less space, but it also means less time, stress and money spent on upkeep.
  2. Let’s assume you save $500 a month on your mortgage payment. In 30 years, you could have an additional $1–1.6 million in the bank to get you through your golden years.
  3. Use the proceeds from selling your current home to pay cash for a smaller one. Just imagine what you could do with no mortgage holding you down! If you can’t pay cash, aim for a 15-year fixed rate mortgage and put at least 10–20% down on your new home. Apply the $500 you saved from downsizing to your new monthly payment. At 3% interest, you could pay off a $200,000 mortgage in less than 10.5 years, saving almost $16,000 in the process.
Realtor.com also addressed downsizing in an article. They suggest that you ask yourself some questions before deciding if downsizing is right for you and your family. Here are two of their questions followed by their answers (in italics) and some additional information that could help.

Q: What kind of lifestyle do I want after I downsize?

A: “For some folks, it’s a matter of living a simpler life focused on family. Some might want to cross off travel destinations on their bucket lists. Some might want a low-maintenance community with high-end upgrades and social events. Decide what you want to achieve from your move first, and you’ll be able to better narrow down your housing options.”
Comments: Many homeowners are taking the profits from the sales of their current homes and splitting it in order to put down payments on smaller homes in their current locations, as well as on vacation/retirement homes where they plan to live when they retire.
This allows them to lock in the home price and mortgage interest rate at today’s values which makes sense financially as both home prices and interest rates are projected to rise.

Q: Have I built up enough equity in my current home to make a profit?

A: “For most homeowners, the answer is yes. This is if they’ve held on to their properties long enough to have positive equity that will be sizable enough to put a large down payment on their next home.”
Comments: A study by Fannie Mae revealed that only 37% of Americans believe that they have significant equity (> 20%) in their current home. In actuality, CoreLogic’s latest Equity Report revealed that 78.9% have greater than 20% equity. That equity could enable you to build the life you’ve always dreamt about.

Bottom Line

If you are debating downsizing your home and want to evaluate the options you currently have, let's meet up to help guide you through the process.

To See More Blogs Like This One Please Visit My Website 
For More Info Please Call 909-697-0823
or Visit