Showing posts with label mortgage. Show all posts

Wednesday, January 30, 2019

Down Payment – How Much Do You Need? By Celina Vazquez

Down Payment – How Much Do You Need? By Celina Vazquez 


Gone are the days when anyone could buy a home with just a promise and signature. No documentation loans allowed virtually anyone to buy a house with no money down with just a simple credit check. After the mortgage meltdown, this all changed. Lenders tightened guidelines and down payments were back.

But how much do you actually need? Must you always find 20% down? The answer might surprise you; there are many ways to buy a home with less than 20% down payment.

 0% Down – There are still two loan programs which allow one to buy a home for no down payment; the VA loan and the USDA loan. The VA loan requires the borrower to be a qualified service person or veteran and the USDA loan is for certain areas under the Department of Agriculture.
 5% Down – Conventional loans with loan limits can allow one to buy a home with as little as 5% down. These loans do have PMI (Private mortgage insurance) which can be eliminated when the loan amount falls below the 20% threshold.
 3 ½ % Down – FHA offers first time home buyers a good home loan for only 3.5% down payment. Again these loans have loan limits and PMI but offer a faster entry into the housing market.

Buying a home doesn’t always mean 20% loan. If you’re considering buying a new home, talk to your lender about your options.


Tuesday, May 30, 2017

Do You Know the Cost of NOT Owning Your Home?


Do You Know the Cost of NOT Owning Your Home?


Do You Know the Cost of NOT Owning Your Home? - Owning a home has great financial benefits, yet many continue renting! Today, let’s look at the financial reasons why owning a home of your own has been a part of the American Dream for as long as America has existed.
Zillow recently reported that:
“With Rents continuing to climb and interest rates staying low, many renters find themselves gazing over the homeownership fence and wondering if the grass really is greener. Leaving aside, for the moment, the difficulties of saving for a down payment, let’s focus on the monthly expenses of owning a home: it turns out that renters currently paying the median rent in many markets could afford to buy a higher-quality property than the typical (read: median-valued) home without increasing their monthly expenses.”

What proof exists that owning is financially better than renting?

1. The latest Rent Vs. Buy Report from Trulia pointed out the top 5 financial benefits of homeownership:
  • Mortgage payments can be fixed while rents go up.
  • Equity in your home can be a financial resource later.
  • You can build wealth without paying capital gain.
  • A mortgage can act as a forced savings account
  • Overall, homeowners can enjoy greater wealth growth than renters.
2. Studies have shown that a homeowner’s net worth is 45x greater than that of a renter.
3. Just a few months ago, we explained that a family buying an average priced home at the beginning of 2017 could build more than $42,000 in family wealth over the next five years.
4. Some argue that renting eliminates the cost of taxes and home repairs, but every potential renter must realize that all the expenses the landlord incurs are already baked into the rent payment –along with a profit margin!!

Bottom Line

Owning a home has always been, and will always be, better from a financial standpoint than renting.

To See More Blogs Like This One Please Visit My Website 
For More Info Please Call 909-697-0823
or Visit

Tuesday, April 11, 2017

Renting or Buying… Either Way You’re Paying a Mortgage

Renting or Buying… Either Way You’re Paying a Mortgage


Renting or Buying… Either Way You’re Paying a Mortgage - There are some people who have not purchased homes because they are uncomfortable taking on the obligation of a mortgage. Everyone should realize that, unless you are living with your parents rent-free, you are paying a mortgage - either yours or your landlord’s.
As Entrepreneur Magazine, a premier source for small business, explained this month in their article, “12 Practical Steps to Getting Rich”:
“While renting on a temporary basis isn't terrible, you should most certainly own the roof over your head if you're serious about your finances. It won't make you rich overnight, but by renting, you're paying someone else's mortgage. In effect, you're making someone else rich.”
Christina Boyle, Senior Vice President and head of the Single-Family Sales & Relationship Management organization at Freddie Mac, explains another benefit of securing a mortgage vs. paying rent:
“With a 30-year fixed rate mortgage, you’ll have the certainty & stability of knowing what your mortgage payment will be for the next 30 years – unlike rents which will continue to rise over the next three decades.”
As an owner, your mortgage payment is a form of ‘forced savings’ which allows you to build equity in your home that you can tap into later in life. As a renter, you guarantee the landlord is the person with that equity.
Interest rates are still at historic lows, making it one of the best times to secure a mortgage and make a move into your dream home. Freddie Mac’s latest report shows that rates across the country were at 4.23% last week.

Bottom Line

Whether you are looking for a primary residence for the first time or are considering a vacation home on the shore, now may be the time to buy.

To See More Blogs Like This One Please Visit My Website 
For More Info Please Call 909-697-0823
or Visit

Thursday, April 6, 2017

What Are the Experts Saying about Mortgage Rates?

What Are the Experts Saying about Mortgage Rates?


What Are the Experts Saying about Mortgage Rates? - Mortgage interest rates have risen over the last few months and projections are that they will continue their upswing throughout 2017. What impact will this have on the housing market? Here is what the experts are saying:
“In 1984, 1994, 2000, and 2013, every time we have rate increases, we have increases in nominal home prices. We expect this to be more pronounced, as there is a big demand-and-supply gap at the present time.”
“The tightening labor market, rising wage growth, high levels of consumer confidence and a millennial generation with a pent-up demand for housing should allow the housing market to weather the storm of gradually rising interest rates.”
“Although we strongly believe that the housing supply-demand imbalance for single-family homes will continue to drive above-average home price appreciation, just as falling mortgage rates aided pricing power on the margin in recent months, we expect the opposite effect to become evident in the coming months. As such, we project year-end home price inflation of 4.8% for 2017 and 4.1% for 2018.”
“A modest increase in mortgage rates won’t have much of an effect on home purchases. A buyer may need to slightly re-evaluate which homes they can afford, but it’s not likely to make an impact on qualifying, in most cases.”
"Our survey data shows that mortgage rates would have to be significantly higher to have any meaningful impact. The house buying power that borrowers have, even with rates below five percent, still remains historically strong."
To See More Blogs Like This One Please Visit My Website 
For More Info Please Call 909-697-0823
or Visit

Tuesday, March 14, 2017

Mortgage Interest Rates Went Up Again… Should I Wait to Buy?


Mortgage Interest Rates Went Up Again… Should I Wait to Buy?


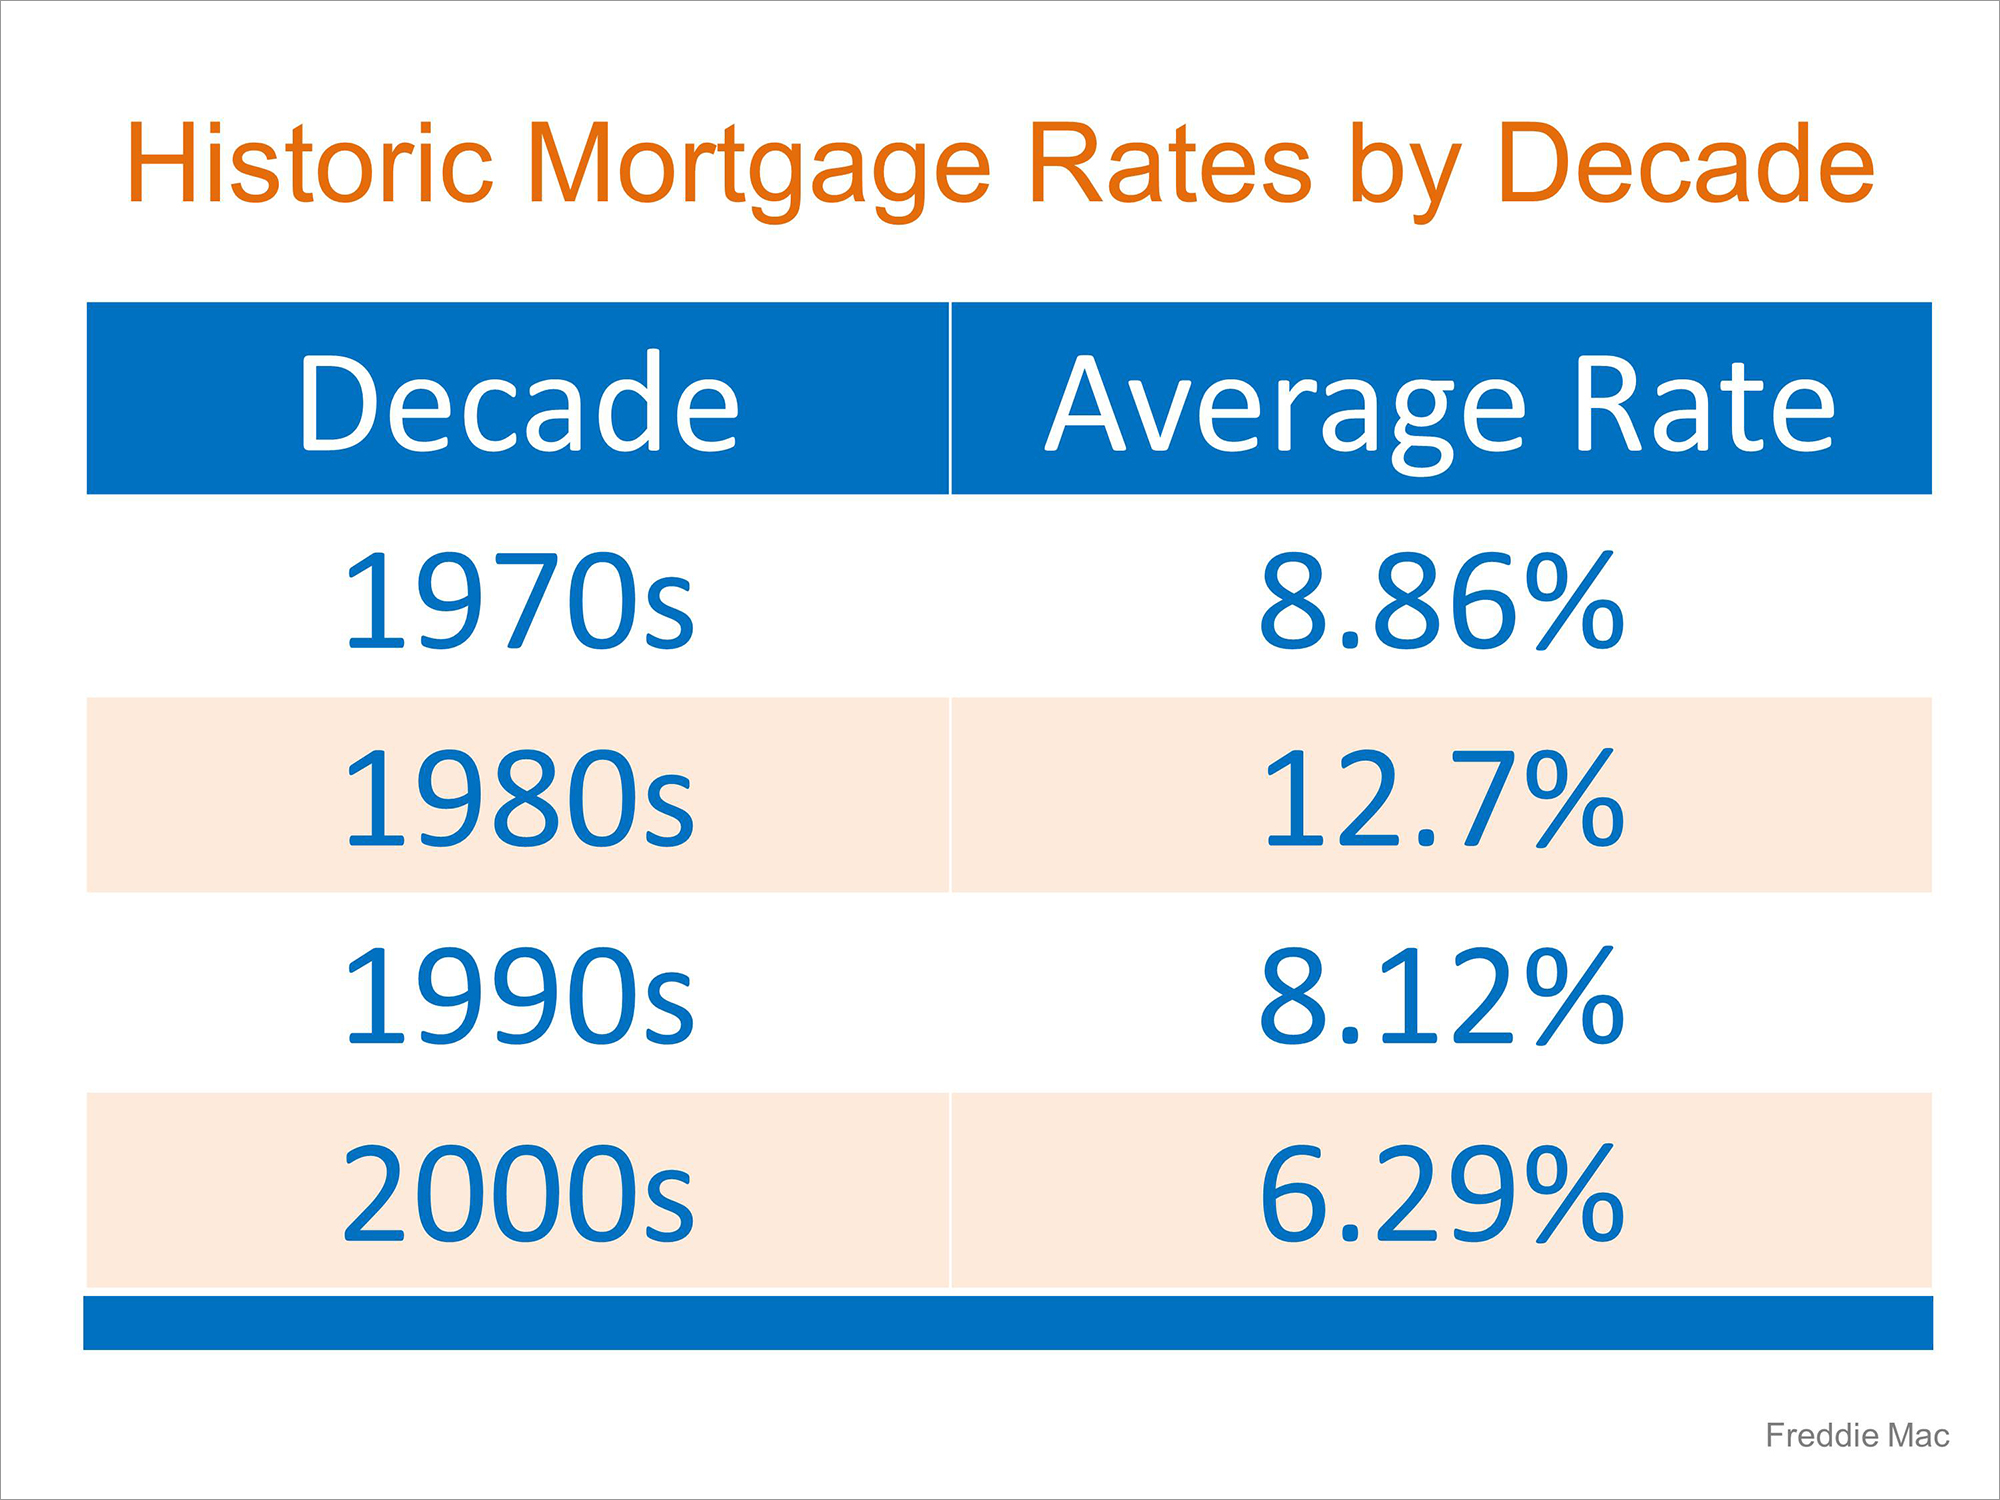
Mortgage Interest Rates Went Up Again… Should I Wait to Buy? - Mortgage interest rates, as reported by Freddie Mac, have increased over the last several weeks. Freddie Mac, along with Fannie Mae, the Mortgage Bankers Association and the National Association of Realtors, is calling for mortgage rates to continue to rise over the next four quarters.
Mortgage Interest Rates Went Up Again… Should I Wait to Buy? | MyKCMThis has caused some purchasers to lament the fact they may no longer be able to get a rate below 4%. However, we must realize that current rates are still at historic lows.
Here is a chart showing the average mortgage interest rate over the last several decades.

Bottom Line

Though you may have missed getting the lowest mortgage rate ever offered, you can still get a better interest rate than your older brother or sister did ten years ago, a lower rate than your parents did twenty years ago, and a better rate than your grandparents did forty years ago.

To See More Blogs Like This One Please Visit My Website 
For More Info Please Call 909-697-0823
or Visit

Thursday, March 2, 2017

Mortgage Rates Impact on 2017 Home Values


Mortgage Rates Impact on 2017 Home Values


Mortgage Rates Impact on 2017 Home Values - There is no doubt that historically low mortgage interest rates were a major impetus to housing recovery over the last several years. However, many industry experts are showing concern about the possible effect that the rising rates will have moving forward.
The Mortgage Bankers Association, Fannie Mae, Freddie Mac and the National Association of Realtors are all projecting that mortgage interest rates will move upward in 2017. Increasing interest rates will definitely impact purchasers and may stifle demand.
In a recent study of industry experts, “rising mortgage Interest rates, and their impact on mortgage affordability” was named by 56% as the force they think will have the most significant impact on U.S. housing in 2017. If rising rates slow demand for housing, home values will be impacted.
To this point, Pulsenomics, recently surveyed a panel of over 100 economists, investment strategists, and housing market analysts, asking the question “In your opinion, at what level will the 30-year fixed rate mortgage rate significantly slow home value appreciation?” The survey revealed the following:

Bottom Line

Most experts believe that rates would need to hit 5% or above to have an impact on home prices.

If You Enjoyed This Blog and Would Like To See More Click Below

For More Info Please Call 909-697-0823
or Visit