Showing posts with label rancho cucamonga real estate agent. Show all posts

Tuesday, May 30, 2017

Do You Know the Cost of NOT Owning Your Home?


Do You Know the Cost of NOT Owning Your Home?


Do You Know the Cost of NOT Owning Your Home? - Owning a home has great financial benefits, yet many continue renting! Today, let’s look at the financial reasons why owning a home of your own has been a part of the American Dream for as long as America has existed.
Zillow recently reported that:
“With Rents continuing to climb and interest rates staying low, many renters find themselves gazing over the homeownership fence and wondering if the grass really is greener. Leaving aside, for the moment, the difficulties of saving for a down payment, let’s focus on the monthly expenses of owning a home: it turns out that renters currently paying the median rent in many markets could afford to buy a higher-quality property than the typical (read: median-valued) home without increasing their monthly expenses.”

What proof exists that owning is financially better than renting?

1. The latest Rent Vs. Buy Report from Trulia pointed out the top 5 financial benefits of homeownership:
  • Mortgage payments can be fixed while rents go up.
  • Equity in your home can be a financial resource later.
  • You can build wealth without paying capital gain.
  • A mortgage can act as a forced savings account
  • Overall, homeowners can enjoy greater wealth growth than renters.
2. Studies have shown that a homeowner’s net worth is 45x greater than that of a renter.
3. Just a few months ago, we explained that a family buying an average priced home at the beginning of 2017 could build more than $42,000 in family wealth over the next five years.
4. Some argue that renting eliminates the cost of taxes and home repairs, but every potential renter must realize that all the expenses the landlord incurs are already baked into the rent payment –along with a profit margin!!

Bottom Line

Owning a home has always been, and will always be, better from a financial standpoint than renting.

To See More Blogs Like This One Please Visit My Website 
For More Info Please Call 909-697-0823
or Visit

Thursday, April 20, 2017

Thinking of Selling? Now Is the Time to Act


Thinking of Selling? Now Is the Time to Act


Thinking of Selling? Now Is the Time to Act - If you thought about selling your house this year, now may be the time to do it. The inventory of homes for sale is well below historic norms and buyer demand is skyrocketing. We were still in high school when we learned the concept of supply and demand: the best time to sell something is when supply of that item is low and demand for that item is high. That defines today’s real estate market.
“The biggest challenge to buyers this spring will be simply finding a home to buy and getting it successfully under contract. That’s because the supply of homes for sale is at an all-time low, and yet demand is strong and getting stronger.”
Smoke goes on to say:
“We started the year with the lowest inventory of homes available for sale that we’ve ever seen on realtor.com. While we did see inventory grow 2% in February, total inventory was down 11% over last year.”
In this type of market, a seller may hold a major negotiating advantage when it comes to price and other aspects of the real estate transaction including the inspection, appraisal and financing contingencies.

Bottom Line

As a potential seller, you are in the driver’s seat right now. It might be time to hit the gas.

To See More Blogs Like This One Please Visit My Website 
For More Info Please Call 909-697-0823
or Visit

Tuesday, April 18, 2017

The 'REAL' News about Housing Affordability


The 'REAL' News about Housing Affordability


The 'REAL' News about Housing Affordability - Some industry experts are claiming that the housing market may be headed for a slowdown as we proceed through 2017, based on rising home prices and a potential jump in mortgage interest rates. One of the data points they use is the Housing Affordability Index, as reported by the National Association of Realtors (NAR).
Here is how NAR defines the index:
“The Housing Affordability Index measures whether or not a typical family earns enough income to qualify for a mortgage loan on a typical home at the national level based on the most recent price and income data.”
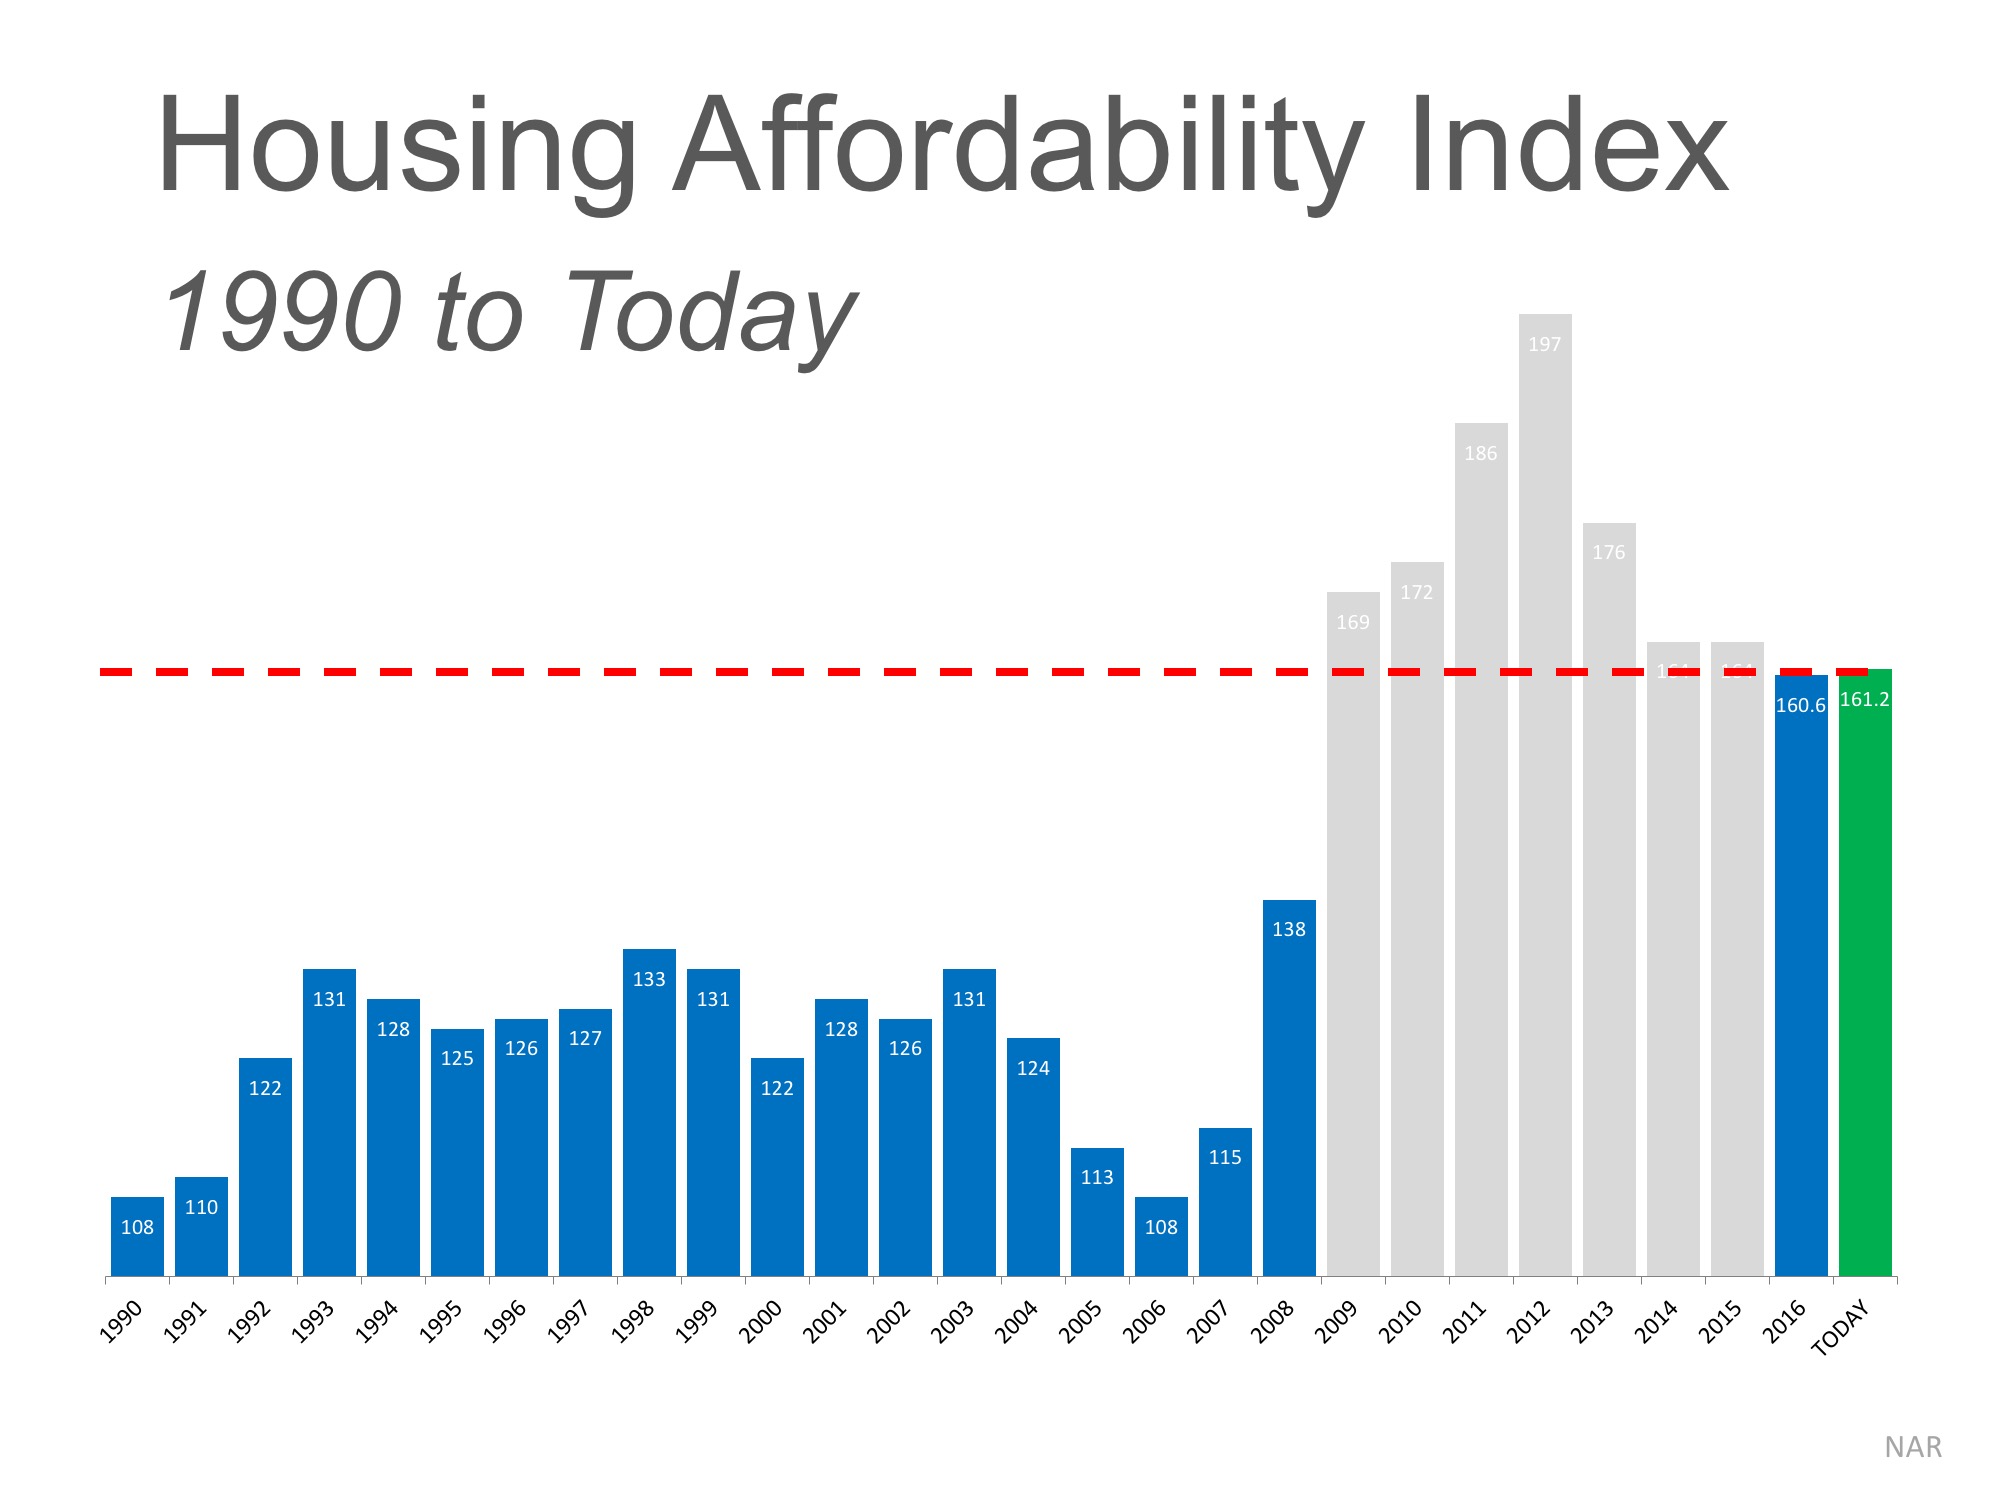
Basically, a value of 100 means a family earning the median income earns enough to qualify for a mortgage on a median-priced home, based on the price and mortgage interest rates at the time. Anything above 100 means the family has more than enough to qualify.
The higher the index, the easier it is to afford a home.

Why the concern?

The index has been declining over the last several years as home values increased. Some are concerned that too many buyers could be priced out of the market.
But, wait a minute…
Though the index skyrocketed from 2009 through 2013, we must realize that during that time, the housing crisis left the market with an overabundance of distressed properties (foreclosures and short sales). All prices dropped dramatically and distressed properties sold at major discounts. Then, mortgage rates fell like a rock.
The market is recovering, and values are coming back nicely. That has caused the index to fall.
However, let’s remove the crisis years (shaded in gray) and look at the current index as compared to the index from 1990 – 2008:
The 'REAL' News about Housing Affordability | MyKCM
Though prices and rates appear to be increasing, we must realize that affordability is composed of three ingredients: home prices, interest rates, and income. And, incomes are finally rising.
ATTOM Data Solutions recently released their Q1 2017 U.S. Home Affordability Index. The report explained:
“Stronger wage growth is the silver lining in this report, outpacing home price growth in more than half of the markets for the first time since Q1 2012, when median home prices were still falling nationwide. If that pattern continues, it will help turn the tide in the eroding home affordability trend.”

Bottom Line

Compared to historic norms, it is still a great time to buy from an affordability standpoint.

To See More Blogs Like This One Please Visit My Website 
For More Info Please Call 909-697-0823
or Visit

Again… You Do Not Need 20% Down to Buy NOW!

Again… You Do Not Need 20% Down to Buy NOW! - A survey by Ipsos found that the American public is still somewhat confused about what is required to qualify for a home mortgage loan in today’s housing market. There are two major misconceptions that we want to address today.

1. Down Payment

The survey revealed that consumers overestimate the down payment funds needed to qualify for a home loan. According to the report, 40% of consumers think a 20% down payment is always required. In actuality, there are many loans written with a down payment of 3% or less.
Many renters may actually be able to enter the housing market sooner than they ever imagined with new programs that have emerged allowing less cash out of pocket.

2. FICO® Scores 

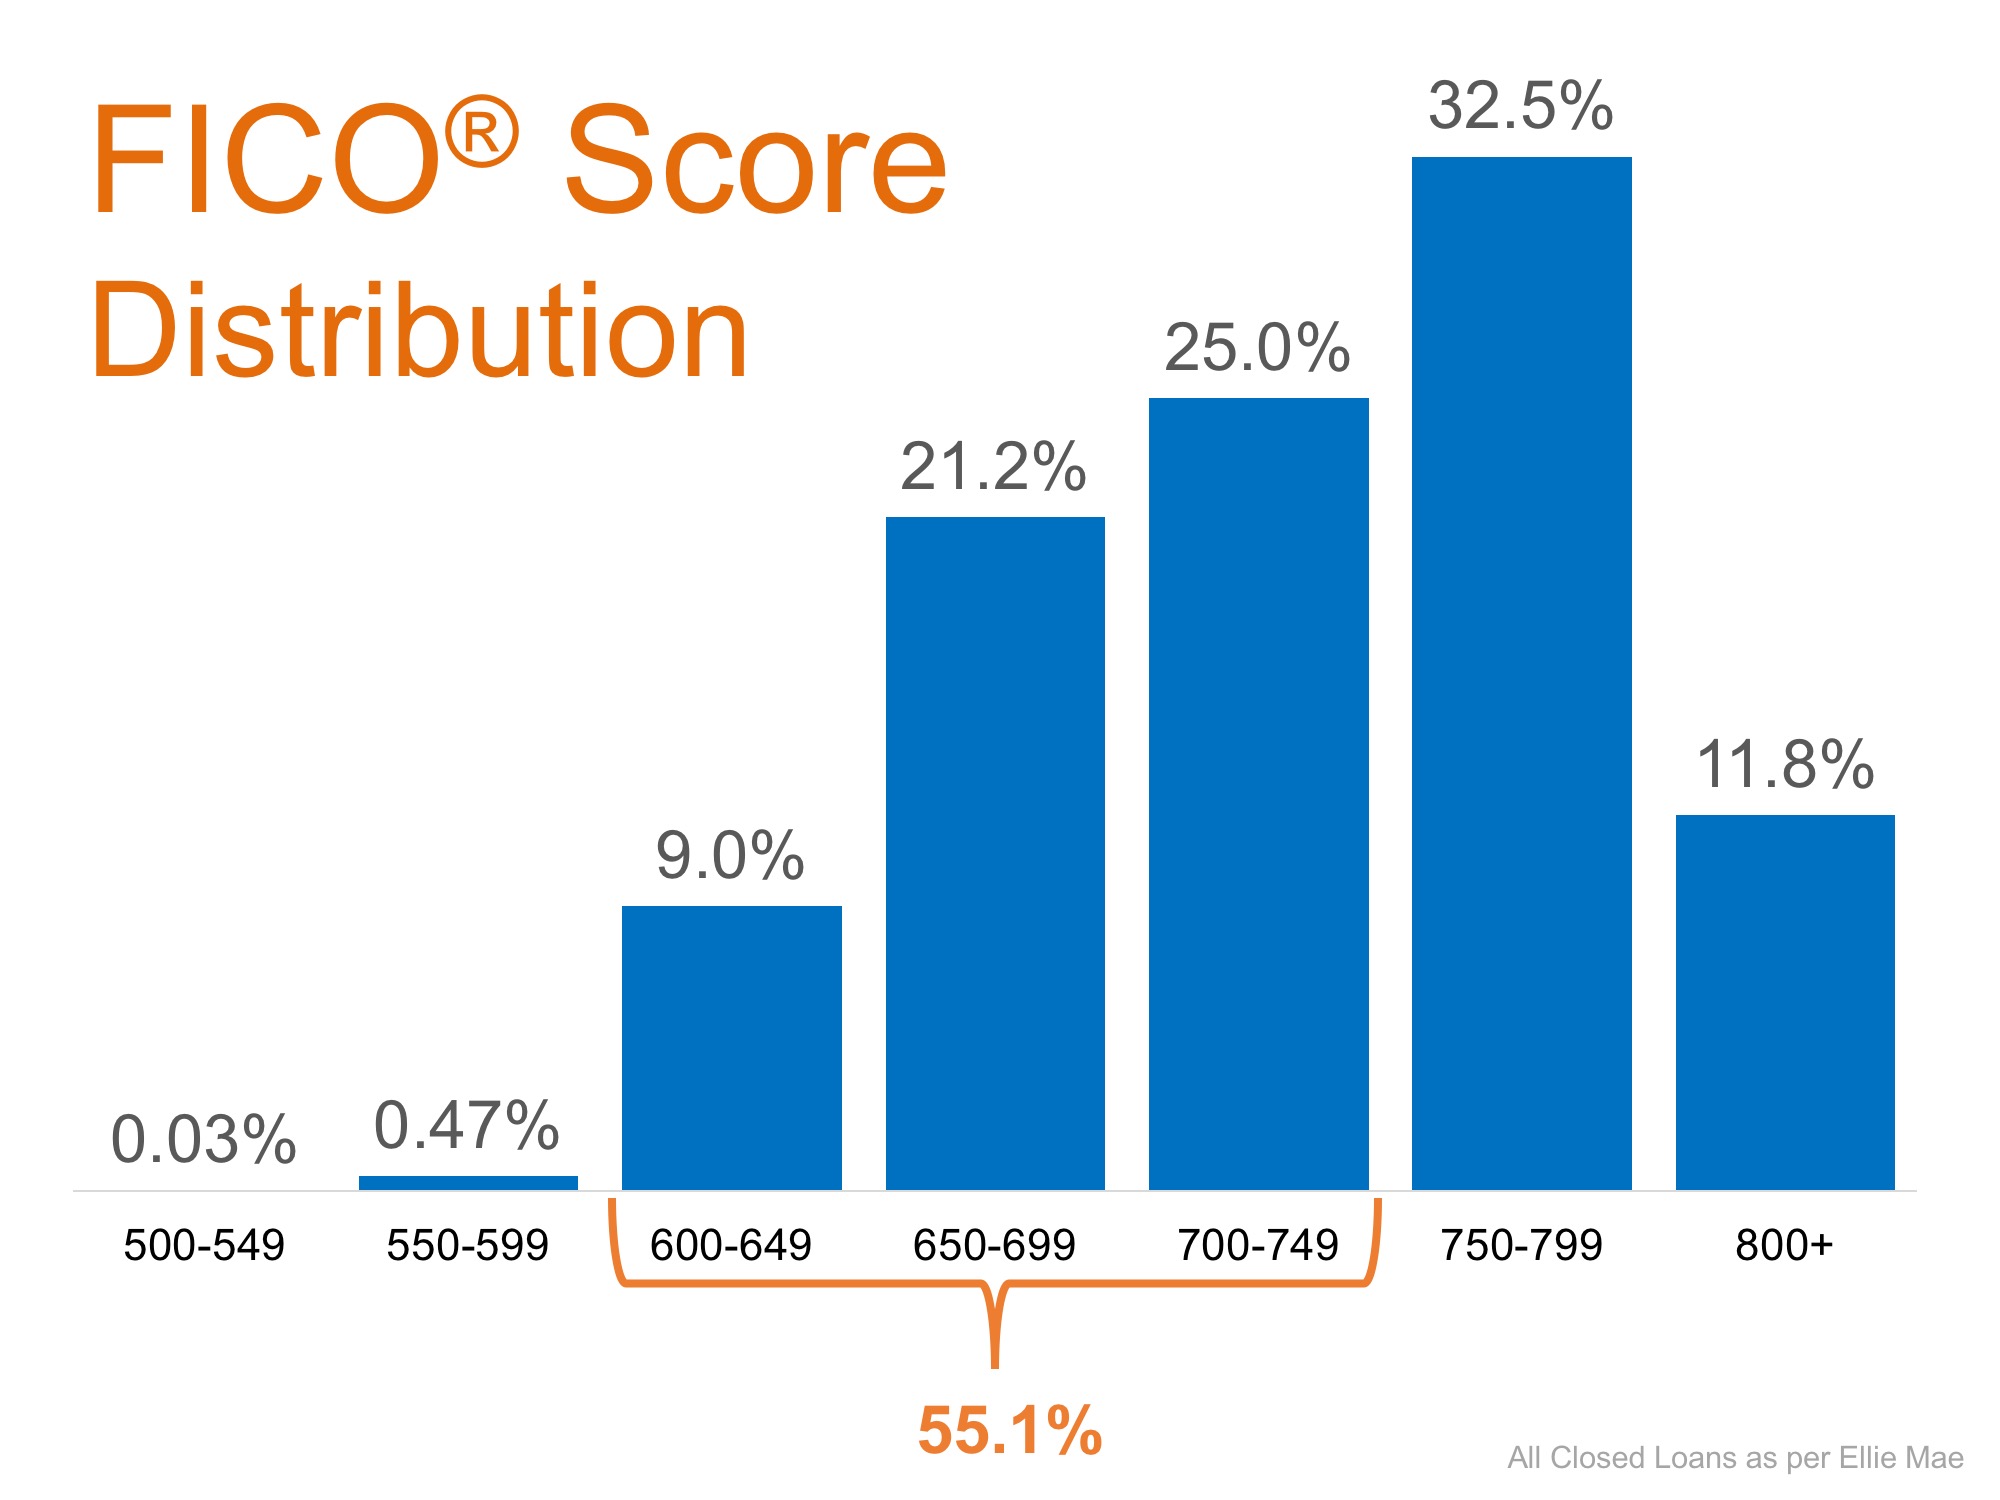
The survey also revealed that 62% of respondents believe they need excellent credit to buy a home, with 43% thinking a “good credit score” is over 780. In actuality, the average FICO® scores of approved conventional and FHA mortgages are much lower.
The average conventional loan closed in February had a credit score of 752, while FHA mortgages closed with a score of 686. The average across all loans closed in February was 720. The chart below shows the distribution of FICO® Scores for all loans approved in February.
Again… You Do Not Need 20% Down to Buy NOW! | MyKCM

Bottom Line

If you are a prospective buyer who is ‘ready’ and ‘willing’ to act now, but are not sure if you are ‘able’ to, let’s sit down to help you understand your true options.

To See More Blogs Like This One Please Visit My Website 
For More Info Please Call 909-697-0823
or Visit