Showing posts with label home loan. Show all posts

Wednesday, September 5, 2018

The Difference Between a Pre-Qualification vs. Pre- Approval

The Difference Between a Pre-Qualification vs. Pre- Approval


There is plenty of real estate terms used in transactions. Needless-to-say it can be confusing
for both buyers and sellers trying to navigate the process. The home loan process might feel
overwhelming and difficult to understand. Both buyers and sellers find terms like “Pre-
Qualification” and “Pre-Approval” used interchangeably, it’s no wonder they find themselves
wondering how to proceed.


Pre-Qualification

The first step in obtaining a home loan is to meet with a lender and discussing their financial
situation. The lender will discuss income, job stability, debt and credit. Once they have
performed a basic review of the qualifications and run credit, they will issue a Pre-Qualification
Letter to the potential buyer. This letter will identify the maximum sales price, down payment
requirement and basic terms of the loan, such as interest rate.
The Pre-Qualification letter is used to provide evidence that the buyer has been reviewed by a
lender who is vouching for their ability to obtain a loan.


Pre-Approval

A Pre-Approval is quite different. In this case, the lender collects all the necessary information
and proof of eligibility and has it reviewed by the lender underwriter for approval. A Pre-
Approval letter is almost like shopping with cash, the only remaining piece of the puzzle is the
property they are buying. 


Tuesday, April 18, 2017

Again… You Do Not Need 20% Down to Buy NOW!

Again… You Do Not Need 20% Down to Buy NOW! - A survey by Ipsos found that the American public is still somewhat confused about what is required to qualify for a home mortgage loan in today’s housing market. There are two major misconceptions that we want to address today.

1. Down Payment

The survey revealed that consumers overestimate the down payment funds needed to qualify for a home loan. According to the report, 40% of consumers think a 20% down payment is always required. In actuality, there are many loans written with a down payment of 3% or less.
Many renters may actually be able to enter the housing market sooner than they ever imagined with new programs that have emerged allowing less cash out of pocket.

2. FICO® Scores 

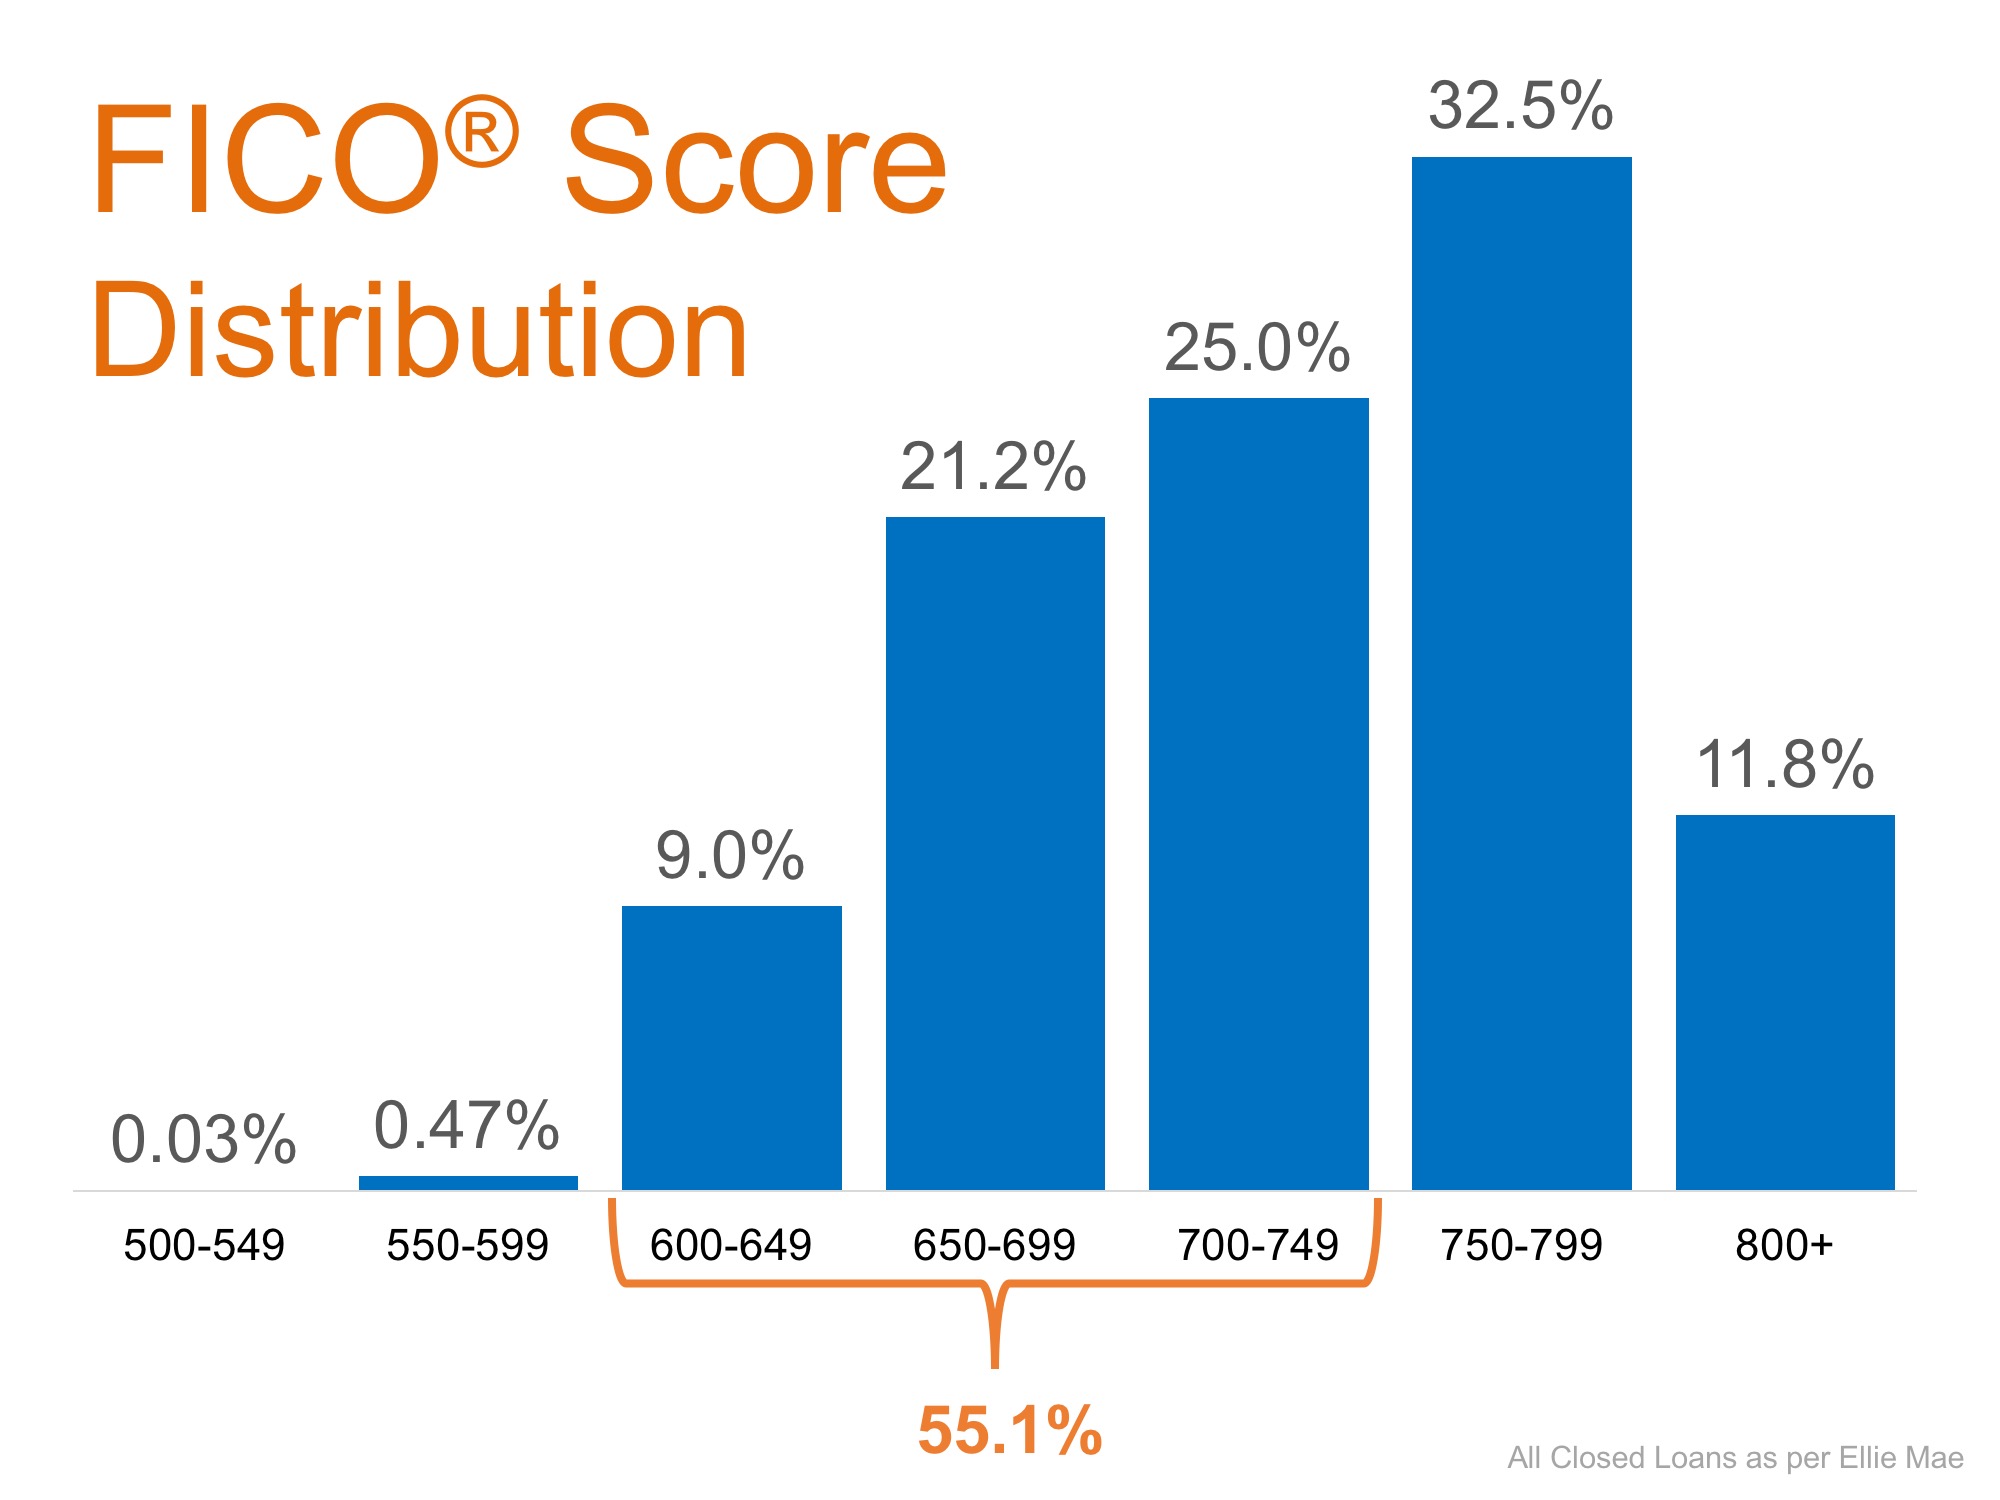
The survey also revealed that 62% of respondents believe they need excellent credit to buy a home, with 43% thinking a “good credit score” is over 780. In actuality, the average FICO® scores of approved conventional and FHA mortgages are much lower.
The average conventional loan closed in February had a credit score of 752, while FHA mortgages closed with a score of 686. The average across all loans closed in February was 720. The chart below shows the distribution of FICO® Scores for all loans approved in February.
Again… You Do Not Need 20% Down to Buy NOW! | MyKCM

Bottom Line

If you are a prospective buyer who is ‘ready’ and ‘willing’ to act now, but are not sure if you are ‘able’ to, let’s sit down to help you understand your true options.

To See More Blogs Like This One Please Visit My Website 
For More Info Please Call 909-697-0823
or Visit