Showing posts with label property manager. Show all posts

Thursday, April 27, 2017

3 Charts That Shout, ‘List Your Home Today!’

3 Charts That Shout, ‘List Your Home Today!’


3 Charts That Shout, ‘List Your Home Today! - In school, we all learned the theory of supply and demand. When the demand for an item is greater than the supply of that item, the price will surely rise.

SUPPLY

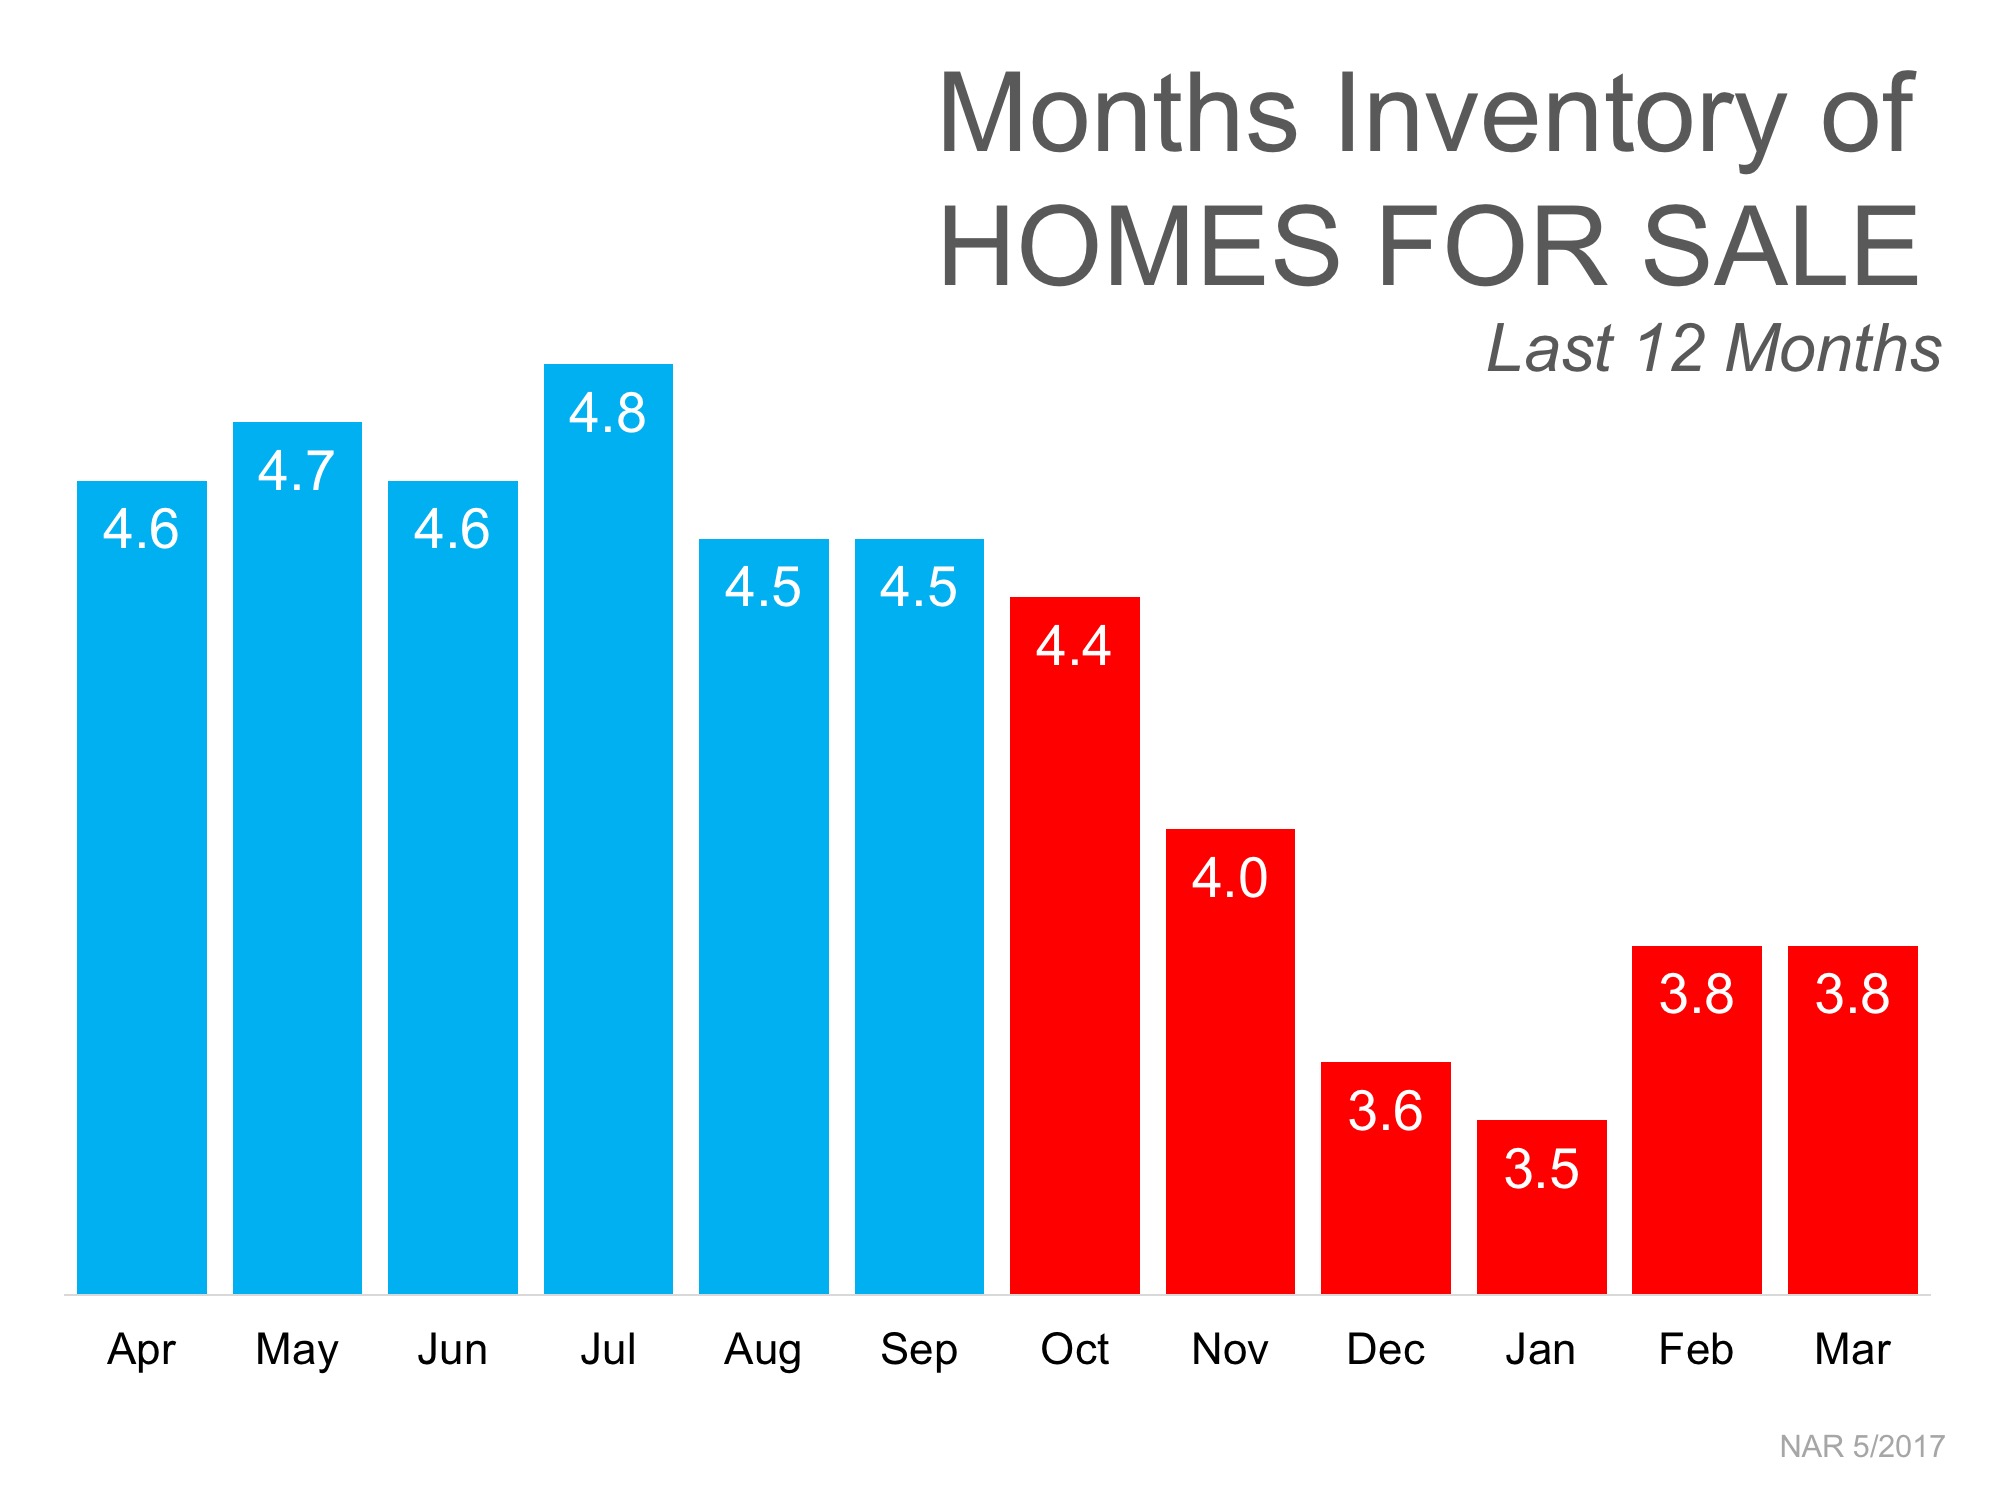
The National Association of Realtors (NAR) recently reported that the inventory of homes for sale stands at a 3.8-month supply. This is considerably lower than the 6-month supply necessary for a normal market.
3 Charts That Shout, ‘List Your Home Today!’ | MyKCM

DEMAND

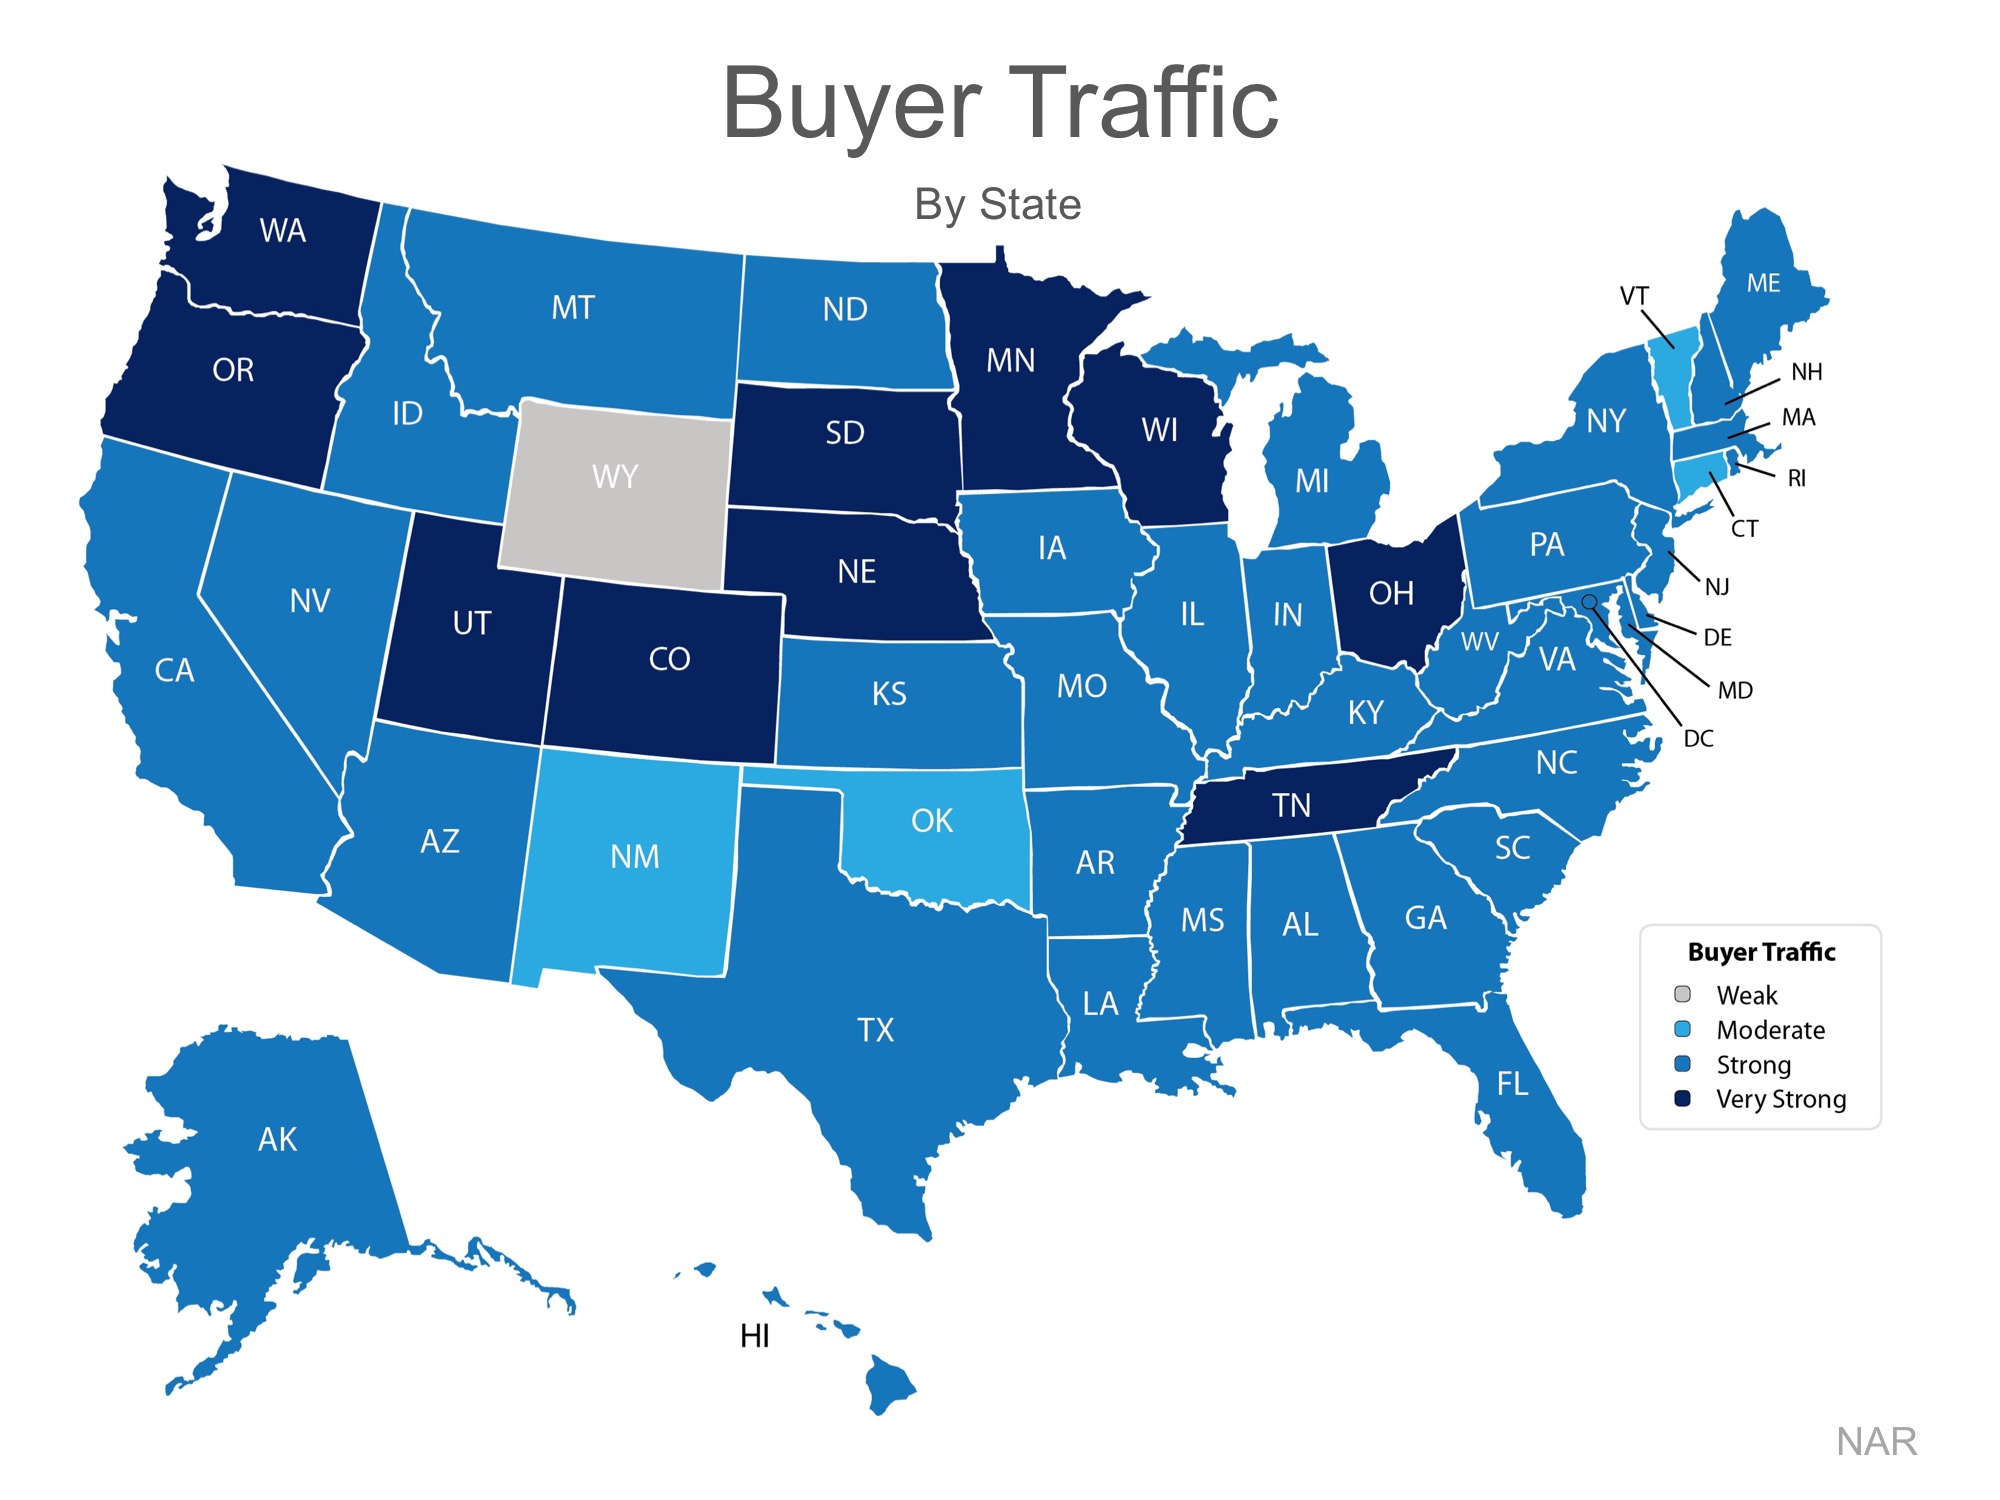
Every month NAR reports on the number of buyers out in the market looking for homes, which is also known as buyer traffic. As seen on the map below, buyer demand in March was strong or very strong in 45 out of 50 states nationwide, and Washington, DC.
3 Charts That Shout, ‘List Your Home Today!’ | MyKCM
Many buyers are being confronted with a very competitive market in which they must compete with other buyers for their dream homes (if they are even able to find a home they wish to purchase).
Listing your house for sale now will allow you to capitalize on the shortage of homes for sale in the market, which will translate into a better pricing situation.

HOME EQUITY

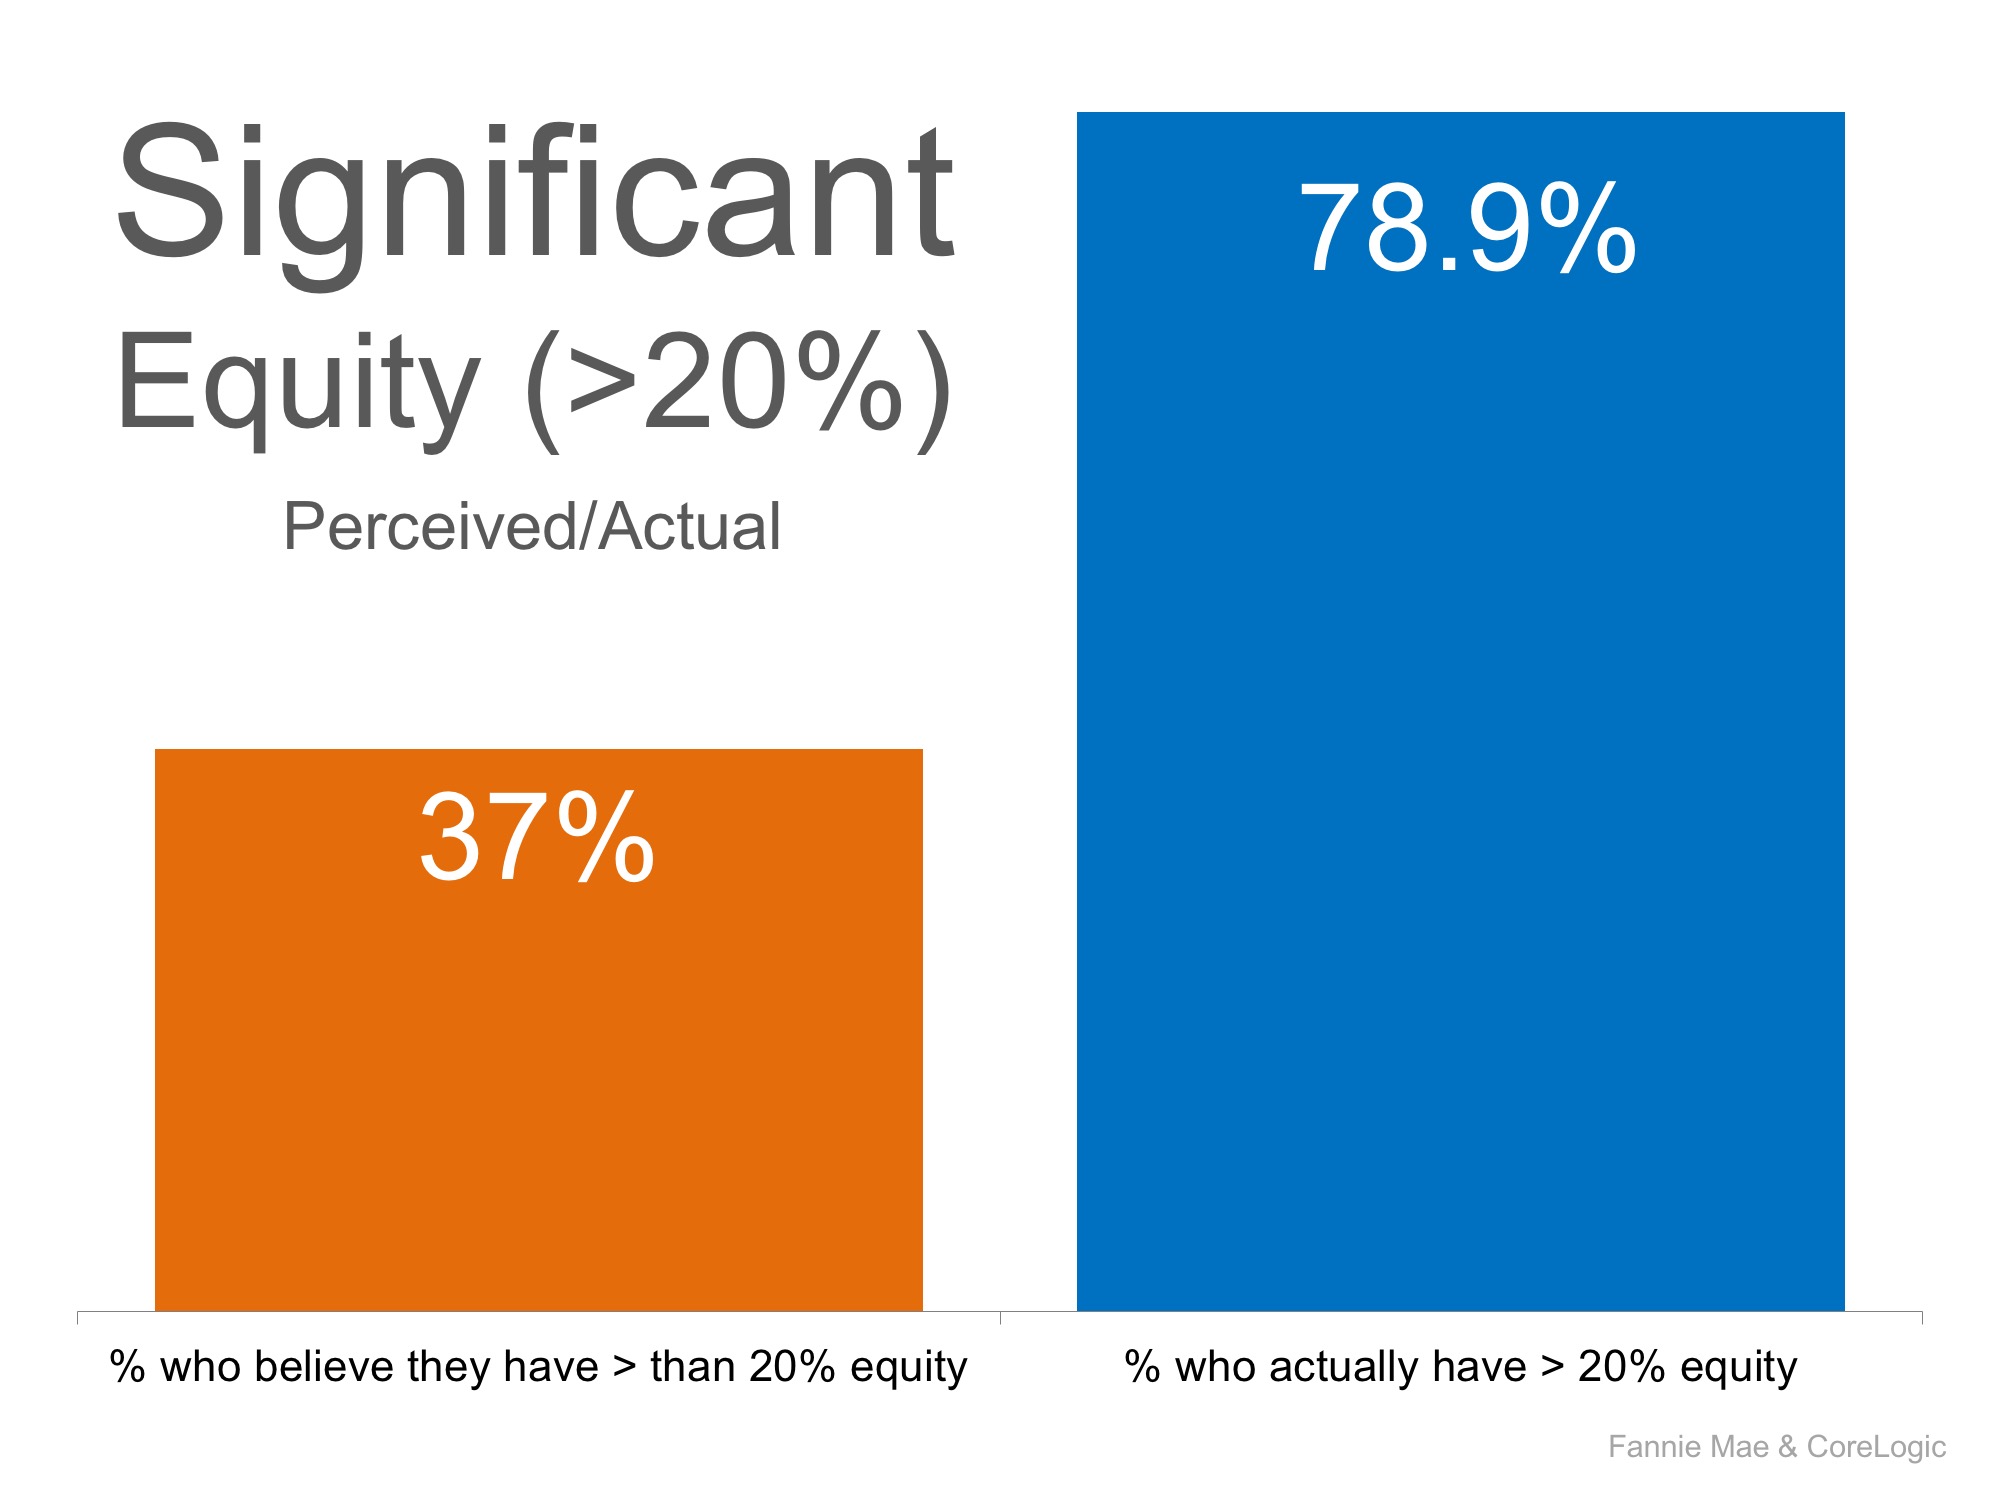
Many homeowners underestimate the amount of equity they currently have in their homes. According to a recent Fannie Mae study, 37% of homeowners believe that they have more than 20% equity in their homes. In reality, CoreLogic’s latest Equity Report tells us that 78.9% actually do!
3 Charts That Shout, ‘List Your Home Today!’ | MyKCM
Many homeowners who are undervaluing the equity they have in their homes may feel trapped, which may be contributing to the lack of inventory in the market.

Bottom Line

If you are debating selling your home this year, let's meet up to evaluate the equity you have in your home, as well as the opportunities available in your market.

To See More Blogs Like This One Please Visit My Website 
For More Info Please Call 909-697-0823
or Visit

Saturday, April 22, 2017

10769 Champagne Rd Rancho Cucamonga Rented in Just 1 Day


Rented!
In Just 1 Day!!!
10769 Champagne Rd
Rancho Cucamonga, CA 91739
Celina Vazquez Broker Realtor of #RealtyMasters & Associates #RanchokCucamonga presents this gorgeous two-story family residence located in North Rancho Cucamonga. This beautiful home features 4 bedrooms, 2.5 bathrooms and 2 car garage with direct access.
With 1,922 Square Feet of living space on a 6,230 Square Feet lot this beautiful home offers everything that you are looking for. Fully remodeled top to bottom this house features a large kitchen with open concept to the family room. All new kitchen counters, new cabinets and new stainless steel appliances. New hardwood, tile and carpet floors throughout. All new plumbing and electrical fixtures and all new paint.
#LosOsosHighSchool, Vineyard Junior High and Banyan Elementary School are the designated schools for this area. The 210 freeway is just minutes away from in. For a private showing contact Celina Vazquez 909-697-0823 or email at celina@celinavazquezrealtor.com

Wednesday, April 19, 2017

Careful…Don’t Get Caught in the Rental Trap!


Careful…Don’t Get Caught in the Rental Trap!


Careful…Don’t Get Caught in the Rental Trap! - There are many benefits to homeownership. One of the top benefits is being able to protect yourself from rising rents by locking in your housing cost for the life of your mortgage.

Don’t Become Trapped 

Jonathan SmokeChief Economist at realtor.comreported on what he calls a “Rental Affordability Crisis.” He warns that,
“Low rental vacancies and a lack of new rental construction are pushing up rents, and we expect that they’ll outpace home price appreciation in the year ahead.”
In the Joint Center for Housing Studies at Harvard University's 2016 State of the Nation’s Housing Report, they revealed that The number of cost-burdened households rose to 21.3 million. Even more troubling, the number with severe burdens (paying more than 50% of income for housing) jumped to a record 11.4 million. These households struggle to save for a rainy day and pay other bills, such as food and healthcare.

It’s Cheaper to Buy Than Rent 

In Smoke’s article, he went on to say,
“Housing is central to the health and well-being of our country and our local communities. In addition, this (rental affordability) crisis threatens the future value of owned housing, as the burdensome level of rents will trap more aspiring owners into a vicious financial cycle in which they cannot save and build a solid credit record to eventually buy a home.”
“While more than 85% of markets have burdensome rents today, it’s perplexing that in more than 75% of the counties across the country, it is actually cheaper to buy than rent a home. So why aren’t those unhappy renters choosing to buy?”

Know Your Options

Perhaps you have already saved enough to buy your first home. HousingWire reported that analysts at Nomura believe:
"It’s not that Millennials and other potential homebuyers aren’t qualified in terms of their credit scores or in how much they have saved for their down payment. 
It’s that they think they’re not qualified or they think that they don’t have a big enough down payment.” (emphasis added)
Many first-time homebuyers who believe that they need a large down payment may be holding themselves back from their dream home. As we have reported before, in many areas of the country, a first-time home buyer can save for a 3% down payment in less than two years. You may have already saved enough!

Bottom Line

Don’t get caught in the trap so many renters are currently in. If you are ready and willing to buy a home, find out if you are able. Let’s get together to determine if you can qualify for a mortgage now!

To See More Blogs Like This One Please Visit My Website 
For More Info Please Call 909-697-0823
or Visit

Tuesday, April 18, 2017

Looking to Move-Up to a Luxury Home? Now’s the Time!

Looking to Move-Up to a Luxury Home? Now’s the Time!


Looking to Move-Up to a Luxury Home? Now’s the Time! - If your house no longer fits your needs and you are planning on buying a luxury home, now is a great time to do so! We recently shared data from Trulia’s Market Mismatch Study which showed that in today’s premium home market, buyers are in control.
The inventory of homes for sale in the luxury market far exceeds those searching to purchase these properties in many areas of the country. This means that homes are often staying on the market longer, or can be found at a discount.
Those who have a starter or trade-up home to sell will find buyers competing, and often entering bidding wars, to be able to call your house their new home.
The sale of your starter or trade-up house will aid in coming up with a larger down payment for your new luxury #home. Even a 5% down payment on a million-dollar home is $50,000.
But not all who are buying luxury properties have a home to sell first.
In a recent Washington post article, Daryl Judy, an associate broker with Washington Fine Properties, gave some insight into what many millennials are choosing to do:
“Some high-earning millennials save money until they are in their early 30s to buy a place and just skip over that starter-home phase. They’ll stay in an apartment until they can afford to pay for the place they want.”

Bottom Line

The best time to sell anything is when demand is high and supply is low. If you are currently in a starter or trade-up house that no longer fits your needs, and are looking to step into a luxury home… Now’s the time to list your house for sale and make your dreams come true.

To See More Blogs Like This One Please Visit My Website 
For More Info Please Call 909-697-0823
or Visit

Friday, April 7, 2017

The Foreclosure Crisis: 10 Years Later


The Foreclosure Crisis: 10 Years Later

The Foreclosure Crisis: 10 Years Later - CoreLogic recently released a report entitled, United States Residential Foreclosure Crisis: 10 Years Later, in which they examined the years leading up to the crisis all the way through to present day.
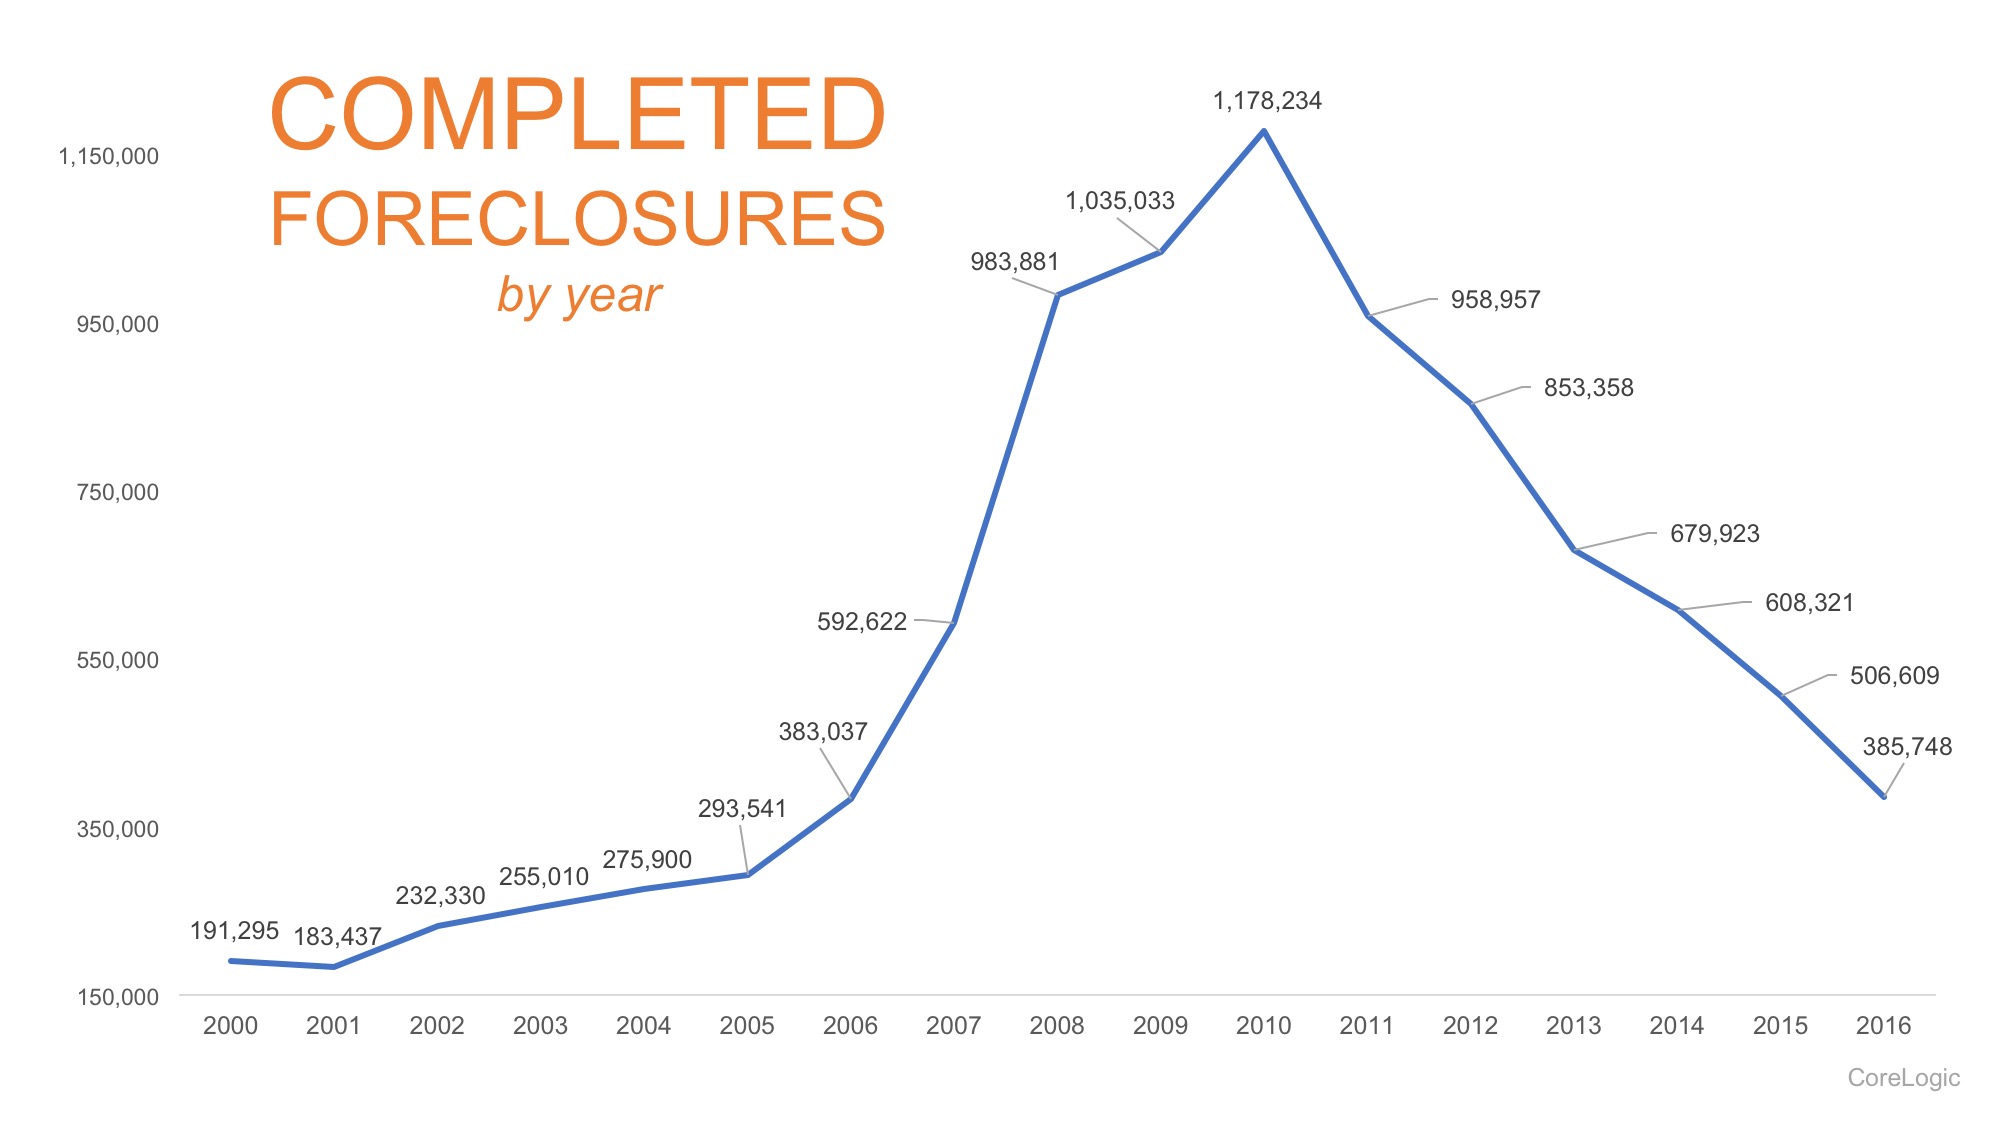
With a peak in 2010 when nearly 1.2 million homes were foreclosed on, over 7.7 million families lost their homes throughout the entire foreclosure crisis.
Dr. Frank NothaftChief Economist for CoreLogic, had this to say,
“The country experienced a wild ride in the mortgage market between 2008 and 2012, with the foreclosure peak occurring in 2010. As we look back over 10 years of the foreclosure crisis, we cannot ignore the connection between jobs and homeownership. A healthy economy is driven by jobs coupled with consumer confidence that usually leads to homeownership.”
Since the peak, foreclosures have been steadily on the decline by nearly 100,000 per year all the way through the end of 2016, as seen in the chart below.
The Foreclosure Crisis: 10 Years Later | MyKCM
If this trend continues, the country will be back to 2005 levels by the end of 2017.

Bottom Line

As the economy continues to improve, and employment numbers increase, the number of completed foreclosures should continue to decrease.
To See More Blogs Like This One Please Visit My Website 
For More Info Please Call 909-697-0823
or Visit