Showing posts with label closing. Show all posts

Wednesday, March 1, 2017

Over Half of All Buyers Are Surprised by Closing Costs

Over Half of All Buyers Are Surprised by Closing Costs


Over Half of All Buyers Are Surprised by Closing Costs - According to a recent survey conducted by ClosingCorp, over half of all homebuyers are surprised by the closing costs required to obtain their mortgage.
After surveying 1,000 first-time and repeat homebuyers, the results revealed that 17% of homebuyers were surprised that closing costs were required at all, while another 35% were stunned by how much higher the fees were than expected.
“Homebuyers reported being most surprised by mortgage insurance, followed by bank fees and points, taxes, title insurance and appraisal fees.”
Bankrate.com recently gathered closing cost data from lenders in every state and Washington, D.C. to be able to share the average costs in each state. The map below was created using the closing costs on a $200,000 mortgage with a 20% down payment.

Keep in mind that if you are in the market for a home above this price range. your costs could be significantly more. According to Freddie Mac,
“Closing costs are typically between 2 and 5% of your purchase price.”

Bottom Line

Speak with your lender and agent early and often to determine how much you’ll be responsible for at closing. Finding out that you’ll need to come up with thousands of dollars right before closing is not a surprise anyone is ever looking forward to.

If You Enjoyed This Blog Please Like and Visit My Website to See Many More

For More Info On Real Estate Or Property Management Please Call 
909-697-0823

Thursday, February 2, 2017

2 Myths That May Be Holding Back Buyers


2 Myths That May Be Holding Back Buyers


#Fannie Mae’s article, “What Consumers (Don’t) Know About Mortgage Qualification Criteria,” revealed that “only 5 to 16 percent of respondents know the correct ranges for key mortgage qualification criteria.”

Myth #1: “I Need a 20% Down Payment”

#Fannie Mae’s survey revealed that #consumers overestimate the down payment funds needed to qualify for a #home loan. According to the report, 76% of Americans either don’t know (40%) or are misinformed (36%) about the minimum down payment required.
Many believe that they need at least 20% down to buy their dream home, but many programs actually let buyers put down as little as 3%.
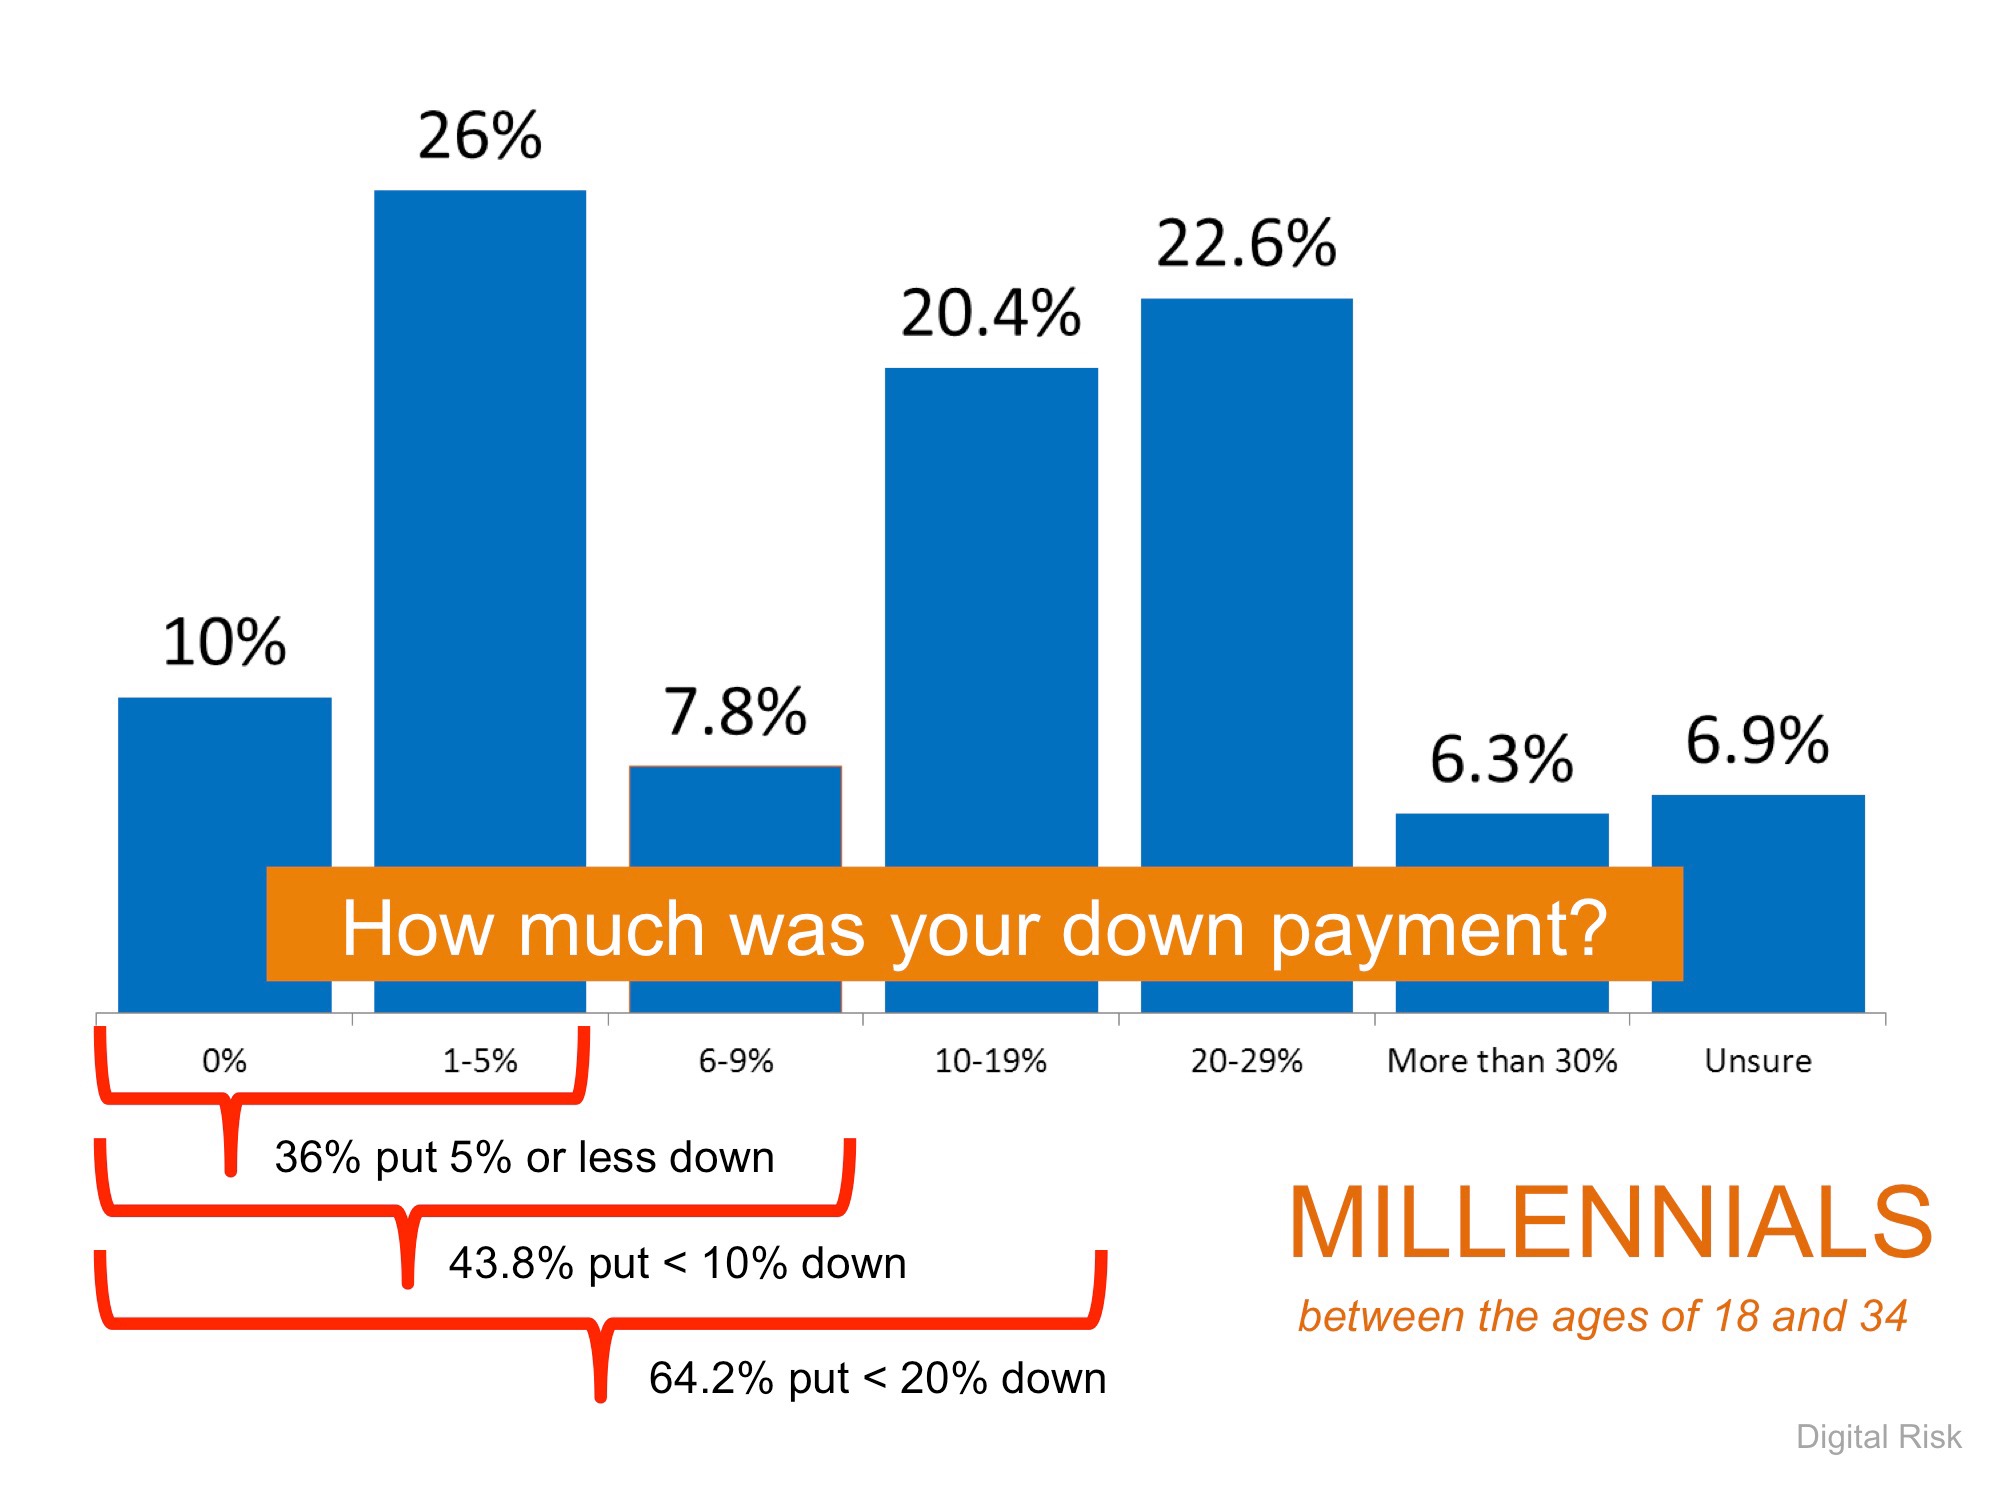
Below are the results of a Digital Risk survey of Millennials who recently purchased a home.
2 Myths That May Be Holding Back Buyers | MyKCM
As you can see, 64.2% were able to purchase their home by putting down less than 20%, with 43.8% putting down less than 10%!

Myth #2: “I need a 780 FICO Score or Higher to Buy”

The survey revealed that 59% of Americans either don’t know (54%) or are misinformed (5%) about what FICO score is necessary to qualify.
Many Americans believe a ‘good’ credit score is 780 or higher.
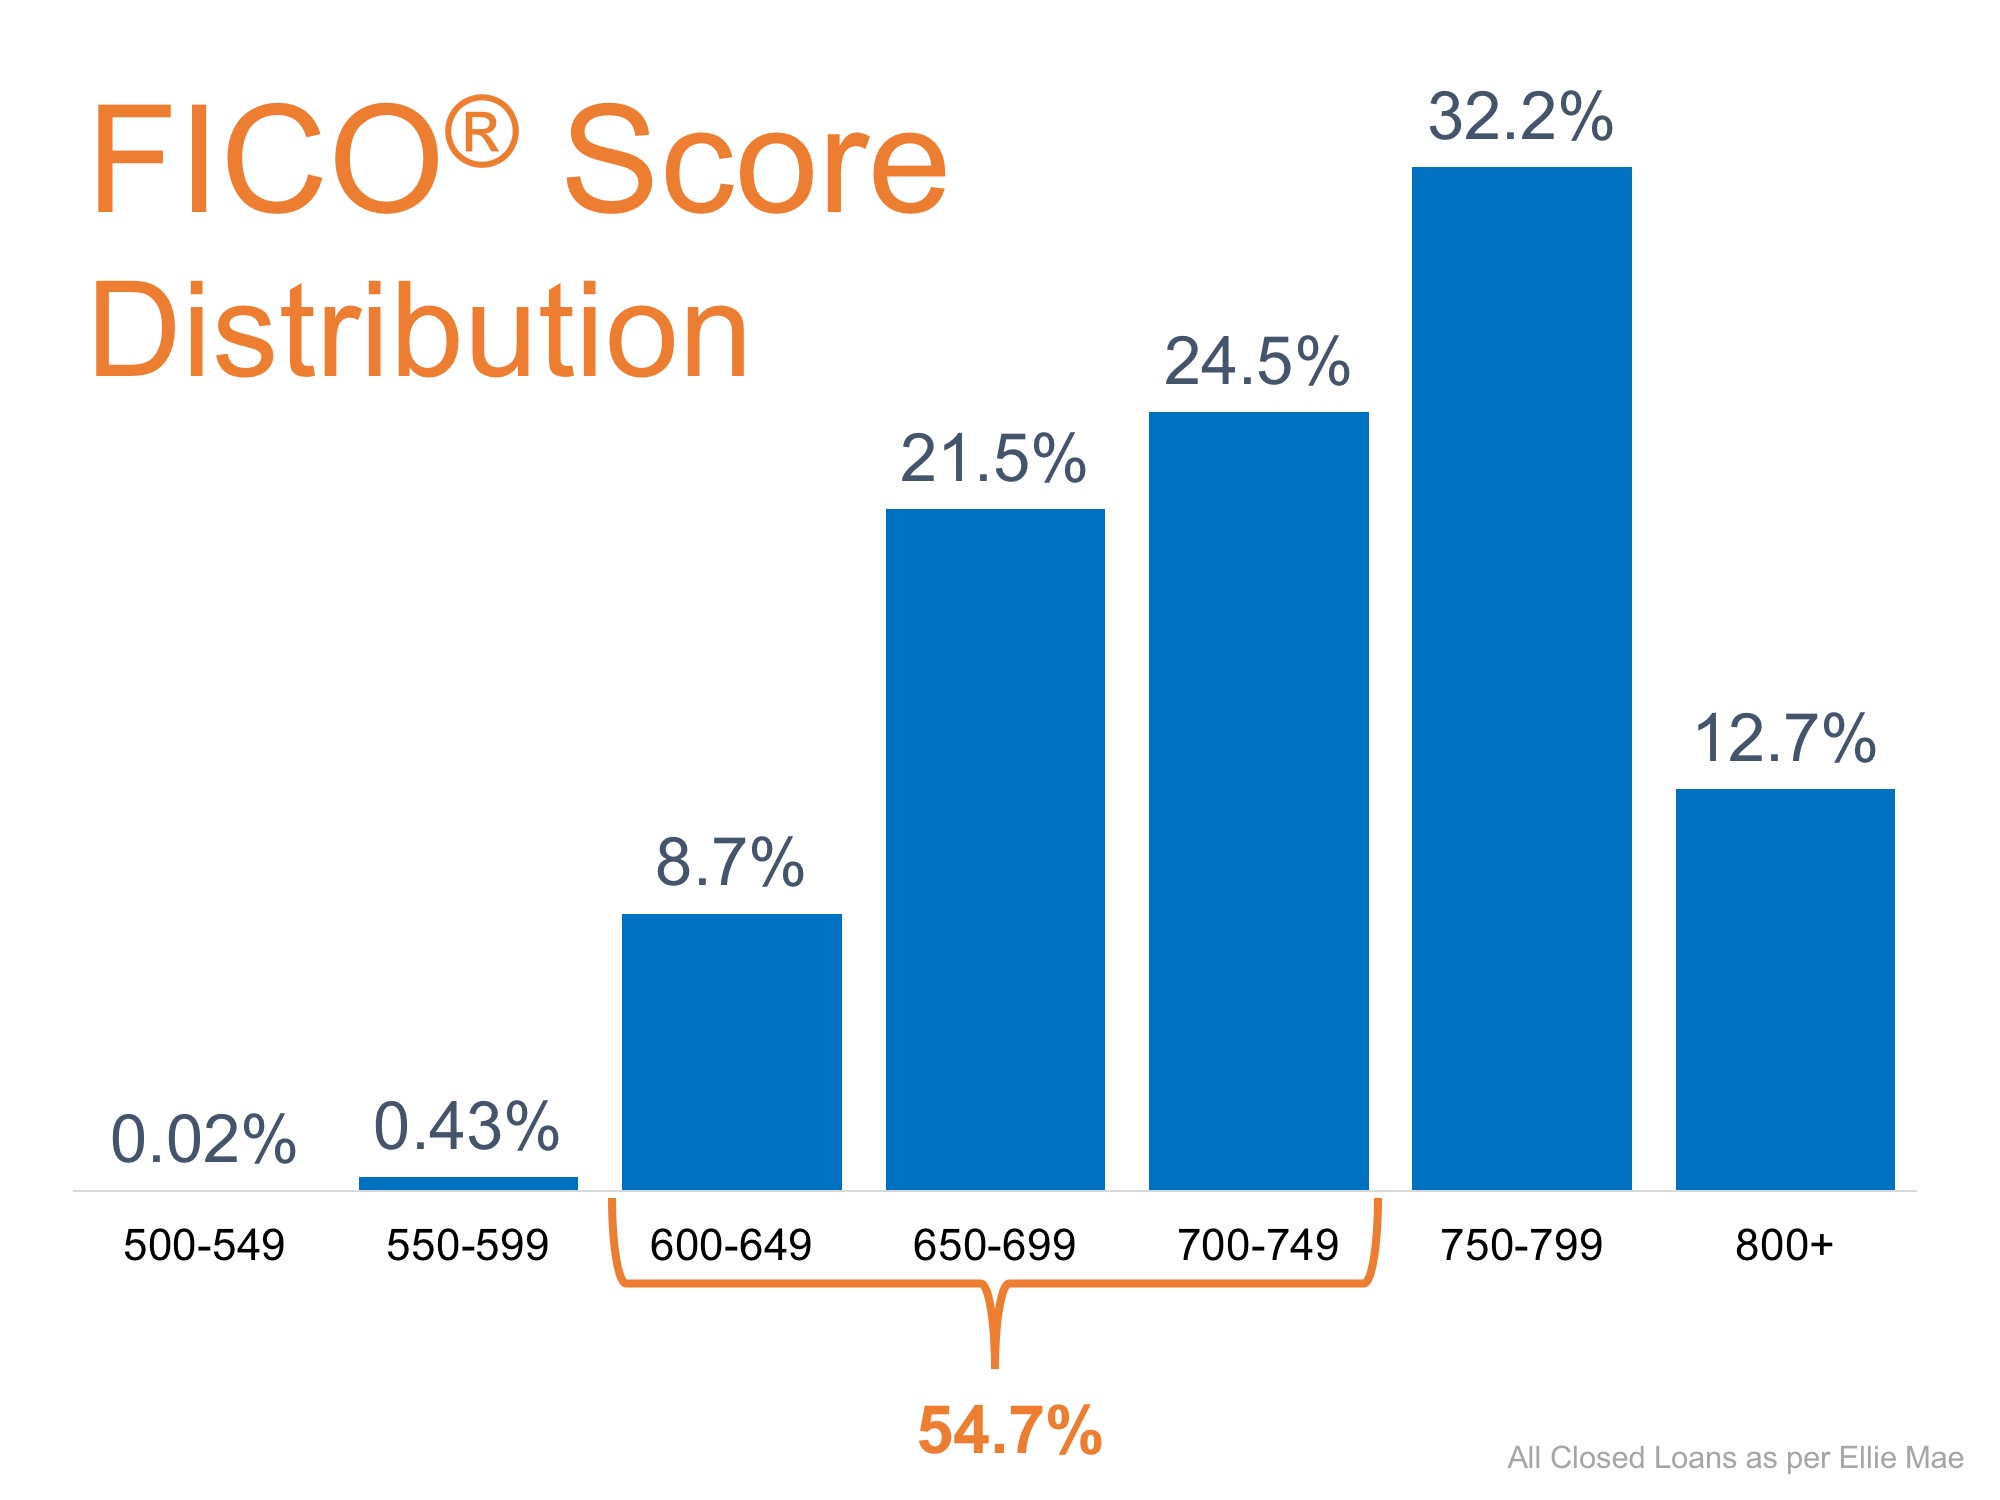
To help debunk this myth, let’s take a look at #Ellie Mae’s latest #Origination Insight Report, which focuses on recently closed (approved) loans. As you can see below, 54.7% of approved mortgages had a credit score of 600-749.
2 Myths That May Be Holding Back Buyers | MyKCM

Bottom Line

Whether buying your first home or moving up to your dream home, knowing your options will make the mortgage process easier. Your dream home may already be within your reach.


For More Information Please Call or Visit: www.celinavazquezrealtor.com
(909)-697-0823

To Read This Article On My Website

Monday, January 23, 2017

Have You Saved Enough for Closing Costs?

Sellers Have You Saved Enough for Closing Costs?

There are many potential #homebuyers, and even # sellers, who believe that they need at least a 20% down #payment in order to buy a #home or move on to their next #home. Time after time, we have dispelled this myth by showing that many loan programs allow you to put down as little as 3% (or 0% with a VA loan).
If you have saved up your down #payment and are ready to start your home search, one other piece of the puzzle is to make sure that you have saved enough for your closing costs.
Freddie Mac defines closing costs as:
“Closing costs, also called settlement fees, will need to be paid when you obtain a mortgage. These are fees charged by people representing your purchase, including your lender, real estate agent, and other third parties involved in the transaction. Closing costs are typically between 2 and 5% of your purchase price.”
We’ve recently heard from many first-time #homebuyers that they wished that someone had let them know that closing costs could be so high. If you think about it, with a low down #payment #program, your closing costs could equal the amount that you saved for your down payment.
Here is a list of just some of the fees/costs that may be included in your closing costs, depending on where the home you wish to purchase is located:
  • Government recording costs
  • Appraisal fees
  • Credit report fees
  • Lender origination fees
  • Title services (insurance, search fees)
  • Tax service fees
  • Survey fees
  • Attorney fees
  • Underwriting fees

Is there any way to avoid paying closing costs?

Work with your lender and real estate agent to see if there are any ways to decrease or defer your closing costs. There are no-closing mortgages #available, but they end up costing you more in the end with a higher interest rate, or by wrapping the closing costs into the total cost of the mortgage (meaning you’ll end up paying interest on your closing costs).
Home #buyers can also negotiate with the seller over who pays these fees. Sometimes the seller will agree to assume the buyer’s closing fees to get the deal finalized, which is known in the industry as ‘seller’s concession.’

Bottom Line

Speak with your lender and agent early and often to determine how much you’ll be responsible for at #closing. Finding out you’ll need to come up with #thousands of #dollars right before closing is not a surprise anyone is ever looking forward to.
For More Info Please Call or Visit At: www.celinvazquezrealtor.com
909-697-0823